
Every investor who holds only their home market has made the same decision. Over the last century and a half that decision paid an Australian seven percent a year in real terms and a Portuguese investor less than one. Nobody chose which of those they were born into.
The number everyone quotes
Equities return about seven percent a year after inflation. That figure comes from one country, measured over the window in which that country won, and it is an average rather than a result. The Jordà-Schularick-Taylor Macrohistory Database lets us look at the alternative histories: annual equity, bond and price data for eighteen advanced economies since 1870, sixteen of which have equity series.
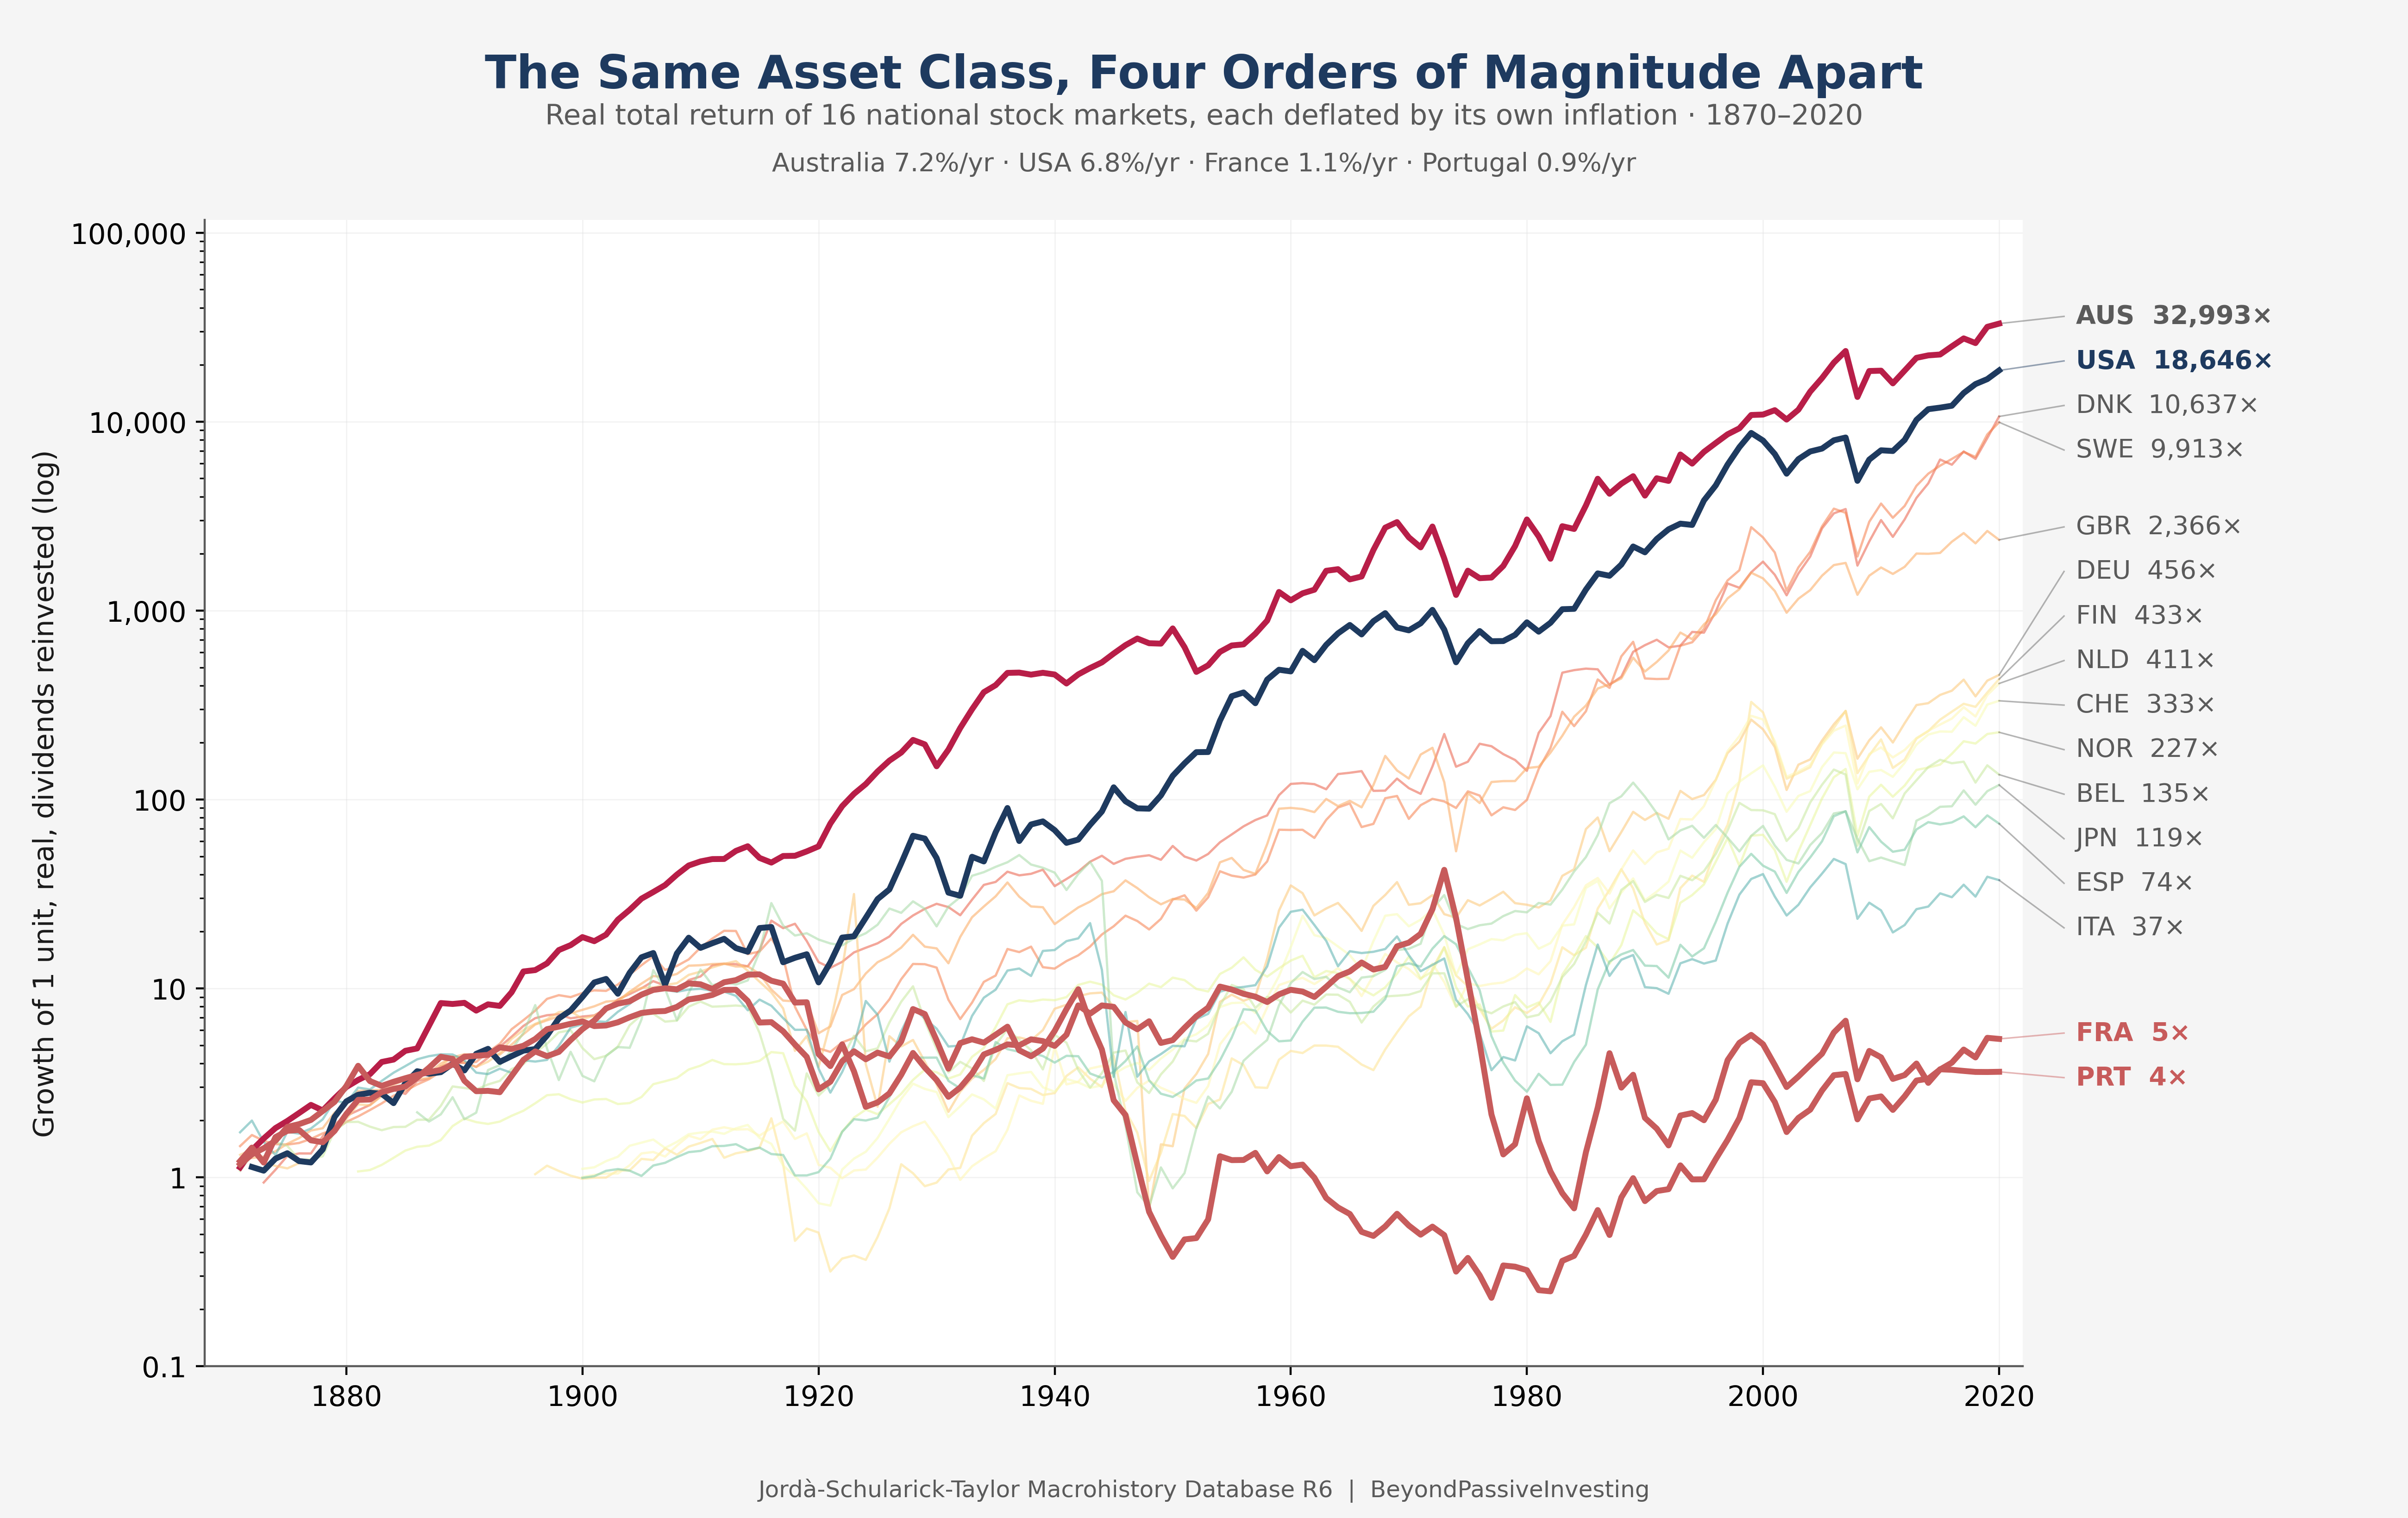
Four orders of magnitude, same asset class, same century and a half. Australia, the United States, France and Portugal all have data from the early 1870s and are directly comparable; the later starters are not, which is why the common-window figures sit under the chart. They sharpen the point rather than softening it. From 1900, in the window all sixteen share, two European markets delivered negative real returns over one hundred and twenty years. A French investor holding French equities ended with less real money than he began with.
The average is not the return
Two numbers get conflated whenever a long-run equity return is quoted. The average of annual returns across these countries is close to the famous seven percent. What the median investor’s money actually did is more than two points lower. The gap is volatility drag, and it is widest exactly where the market was interesting enough to be worth owning.
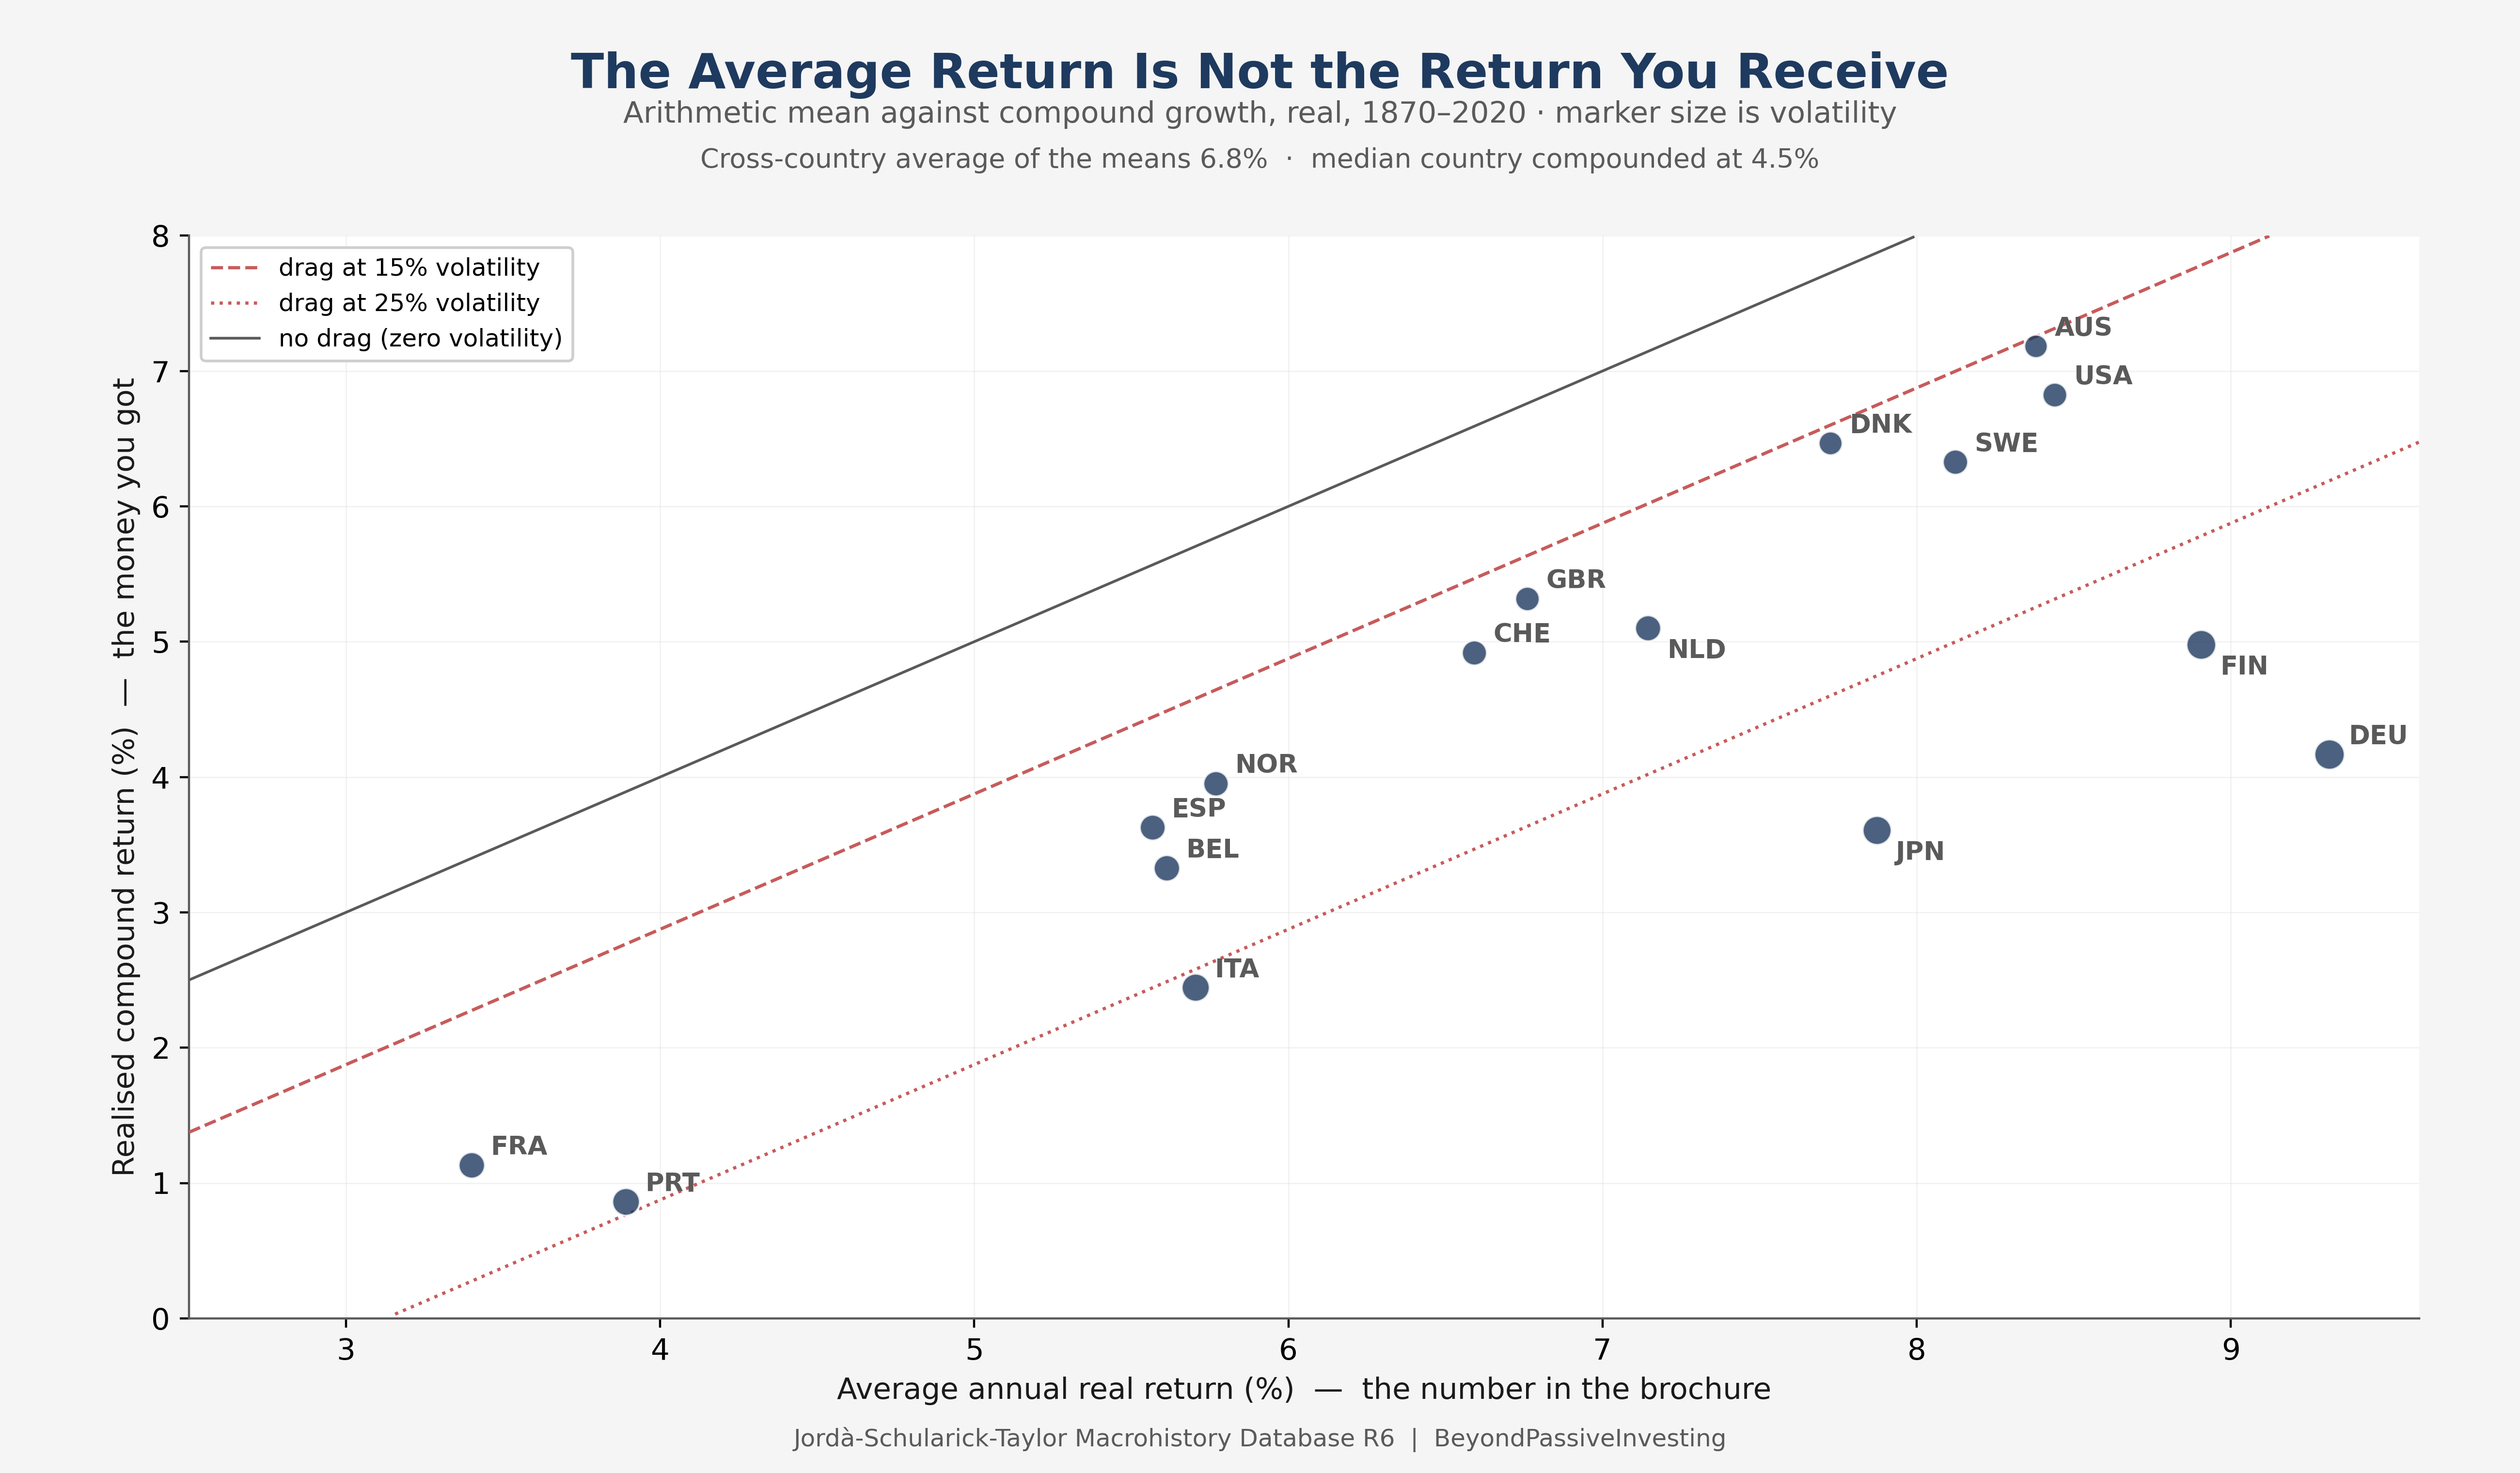
Every return quoted here is a compound annual growth rate, the constant rate that turns the starting sum into the ending sum, because that is what an investor receives. Arithmetic means appear only in the chart above, where the difference between the two is the subject.
Underneath that sits a second confusion, and it matters more. An average across sixteen countries is an average over parallel worlds. No investor lives in sixteen countries. He gets one path, in one place, over one lifetime, and the statistic describing a population is not the statistic describing a single realisation drawn from it. Physics calls this the difference between an ensemble average and a time average, and the two coincide only under conditions national stock markets do not satisfy. Peters argues this is not a technical detail but the foundational error in how economics treats risk. Quote the long-run equity premium at an individual and you have handed him a quantity computed across worlds he will never occupy.
How long could you be wrong
The useful question is not what the average was but how long a reasonable person could hold a reasonable asset and still be wrong. That has an answer, and it is measured in years.
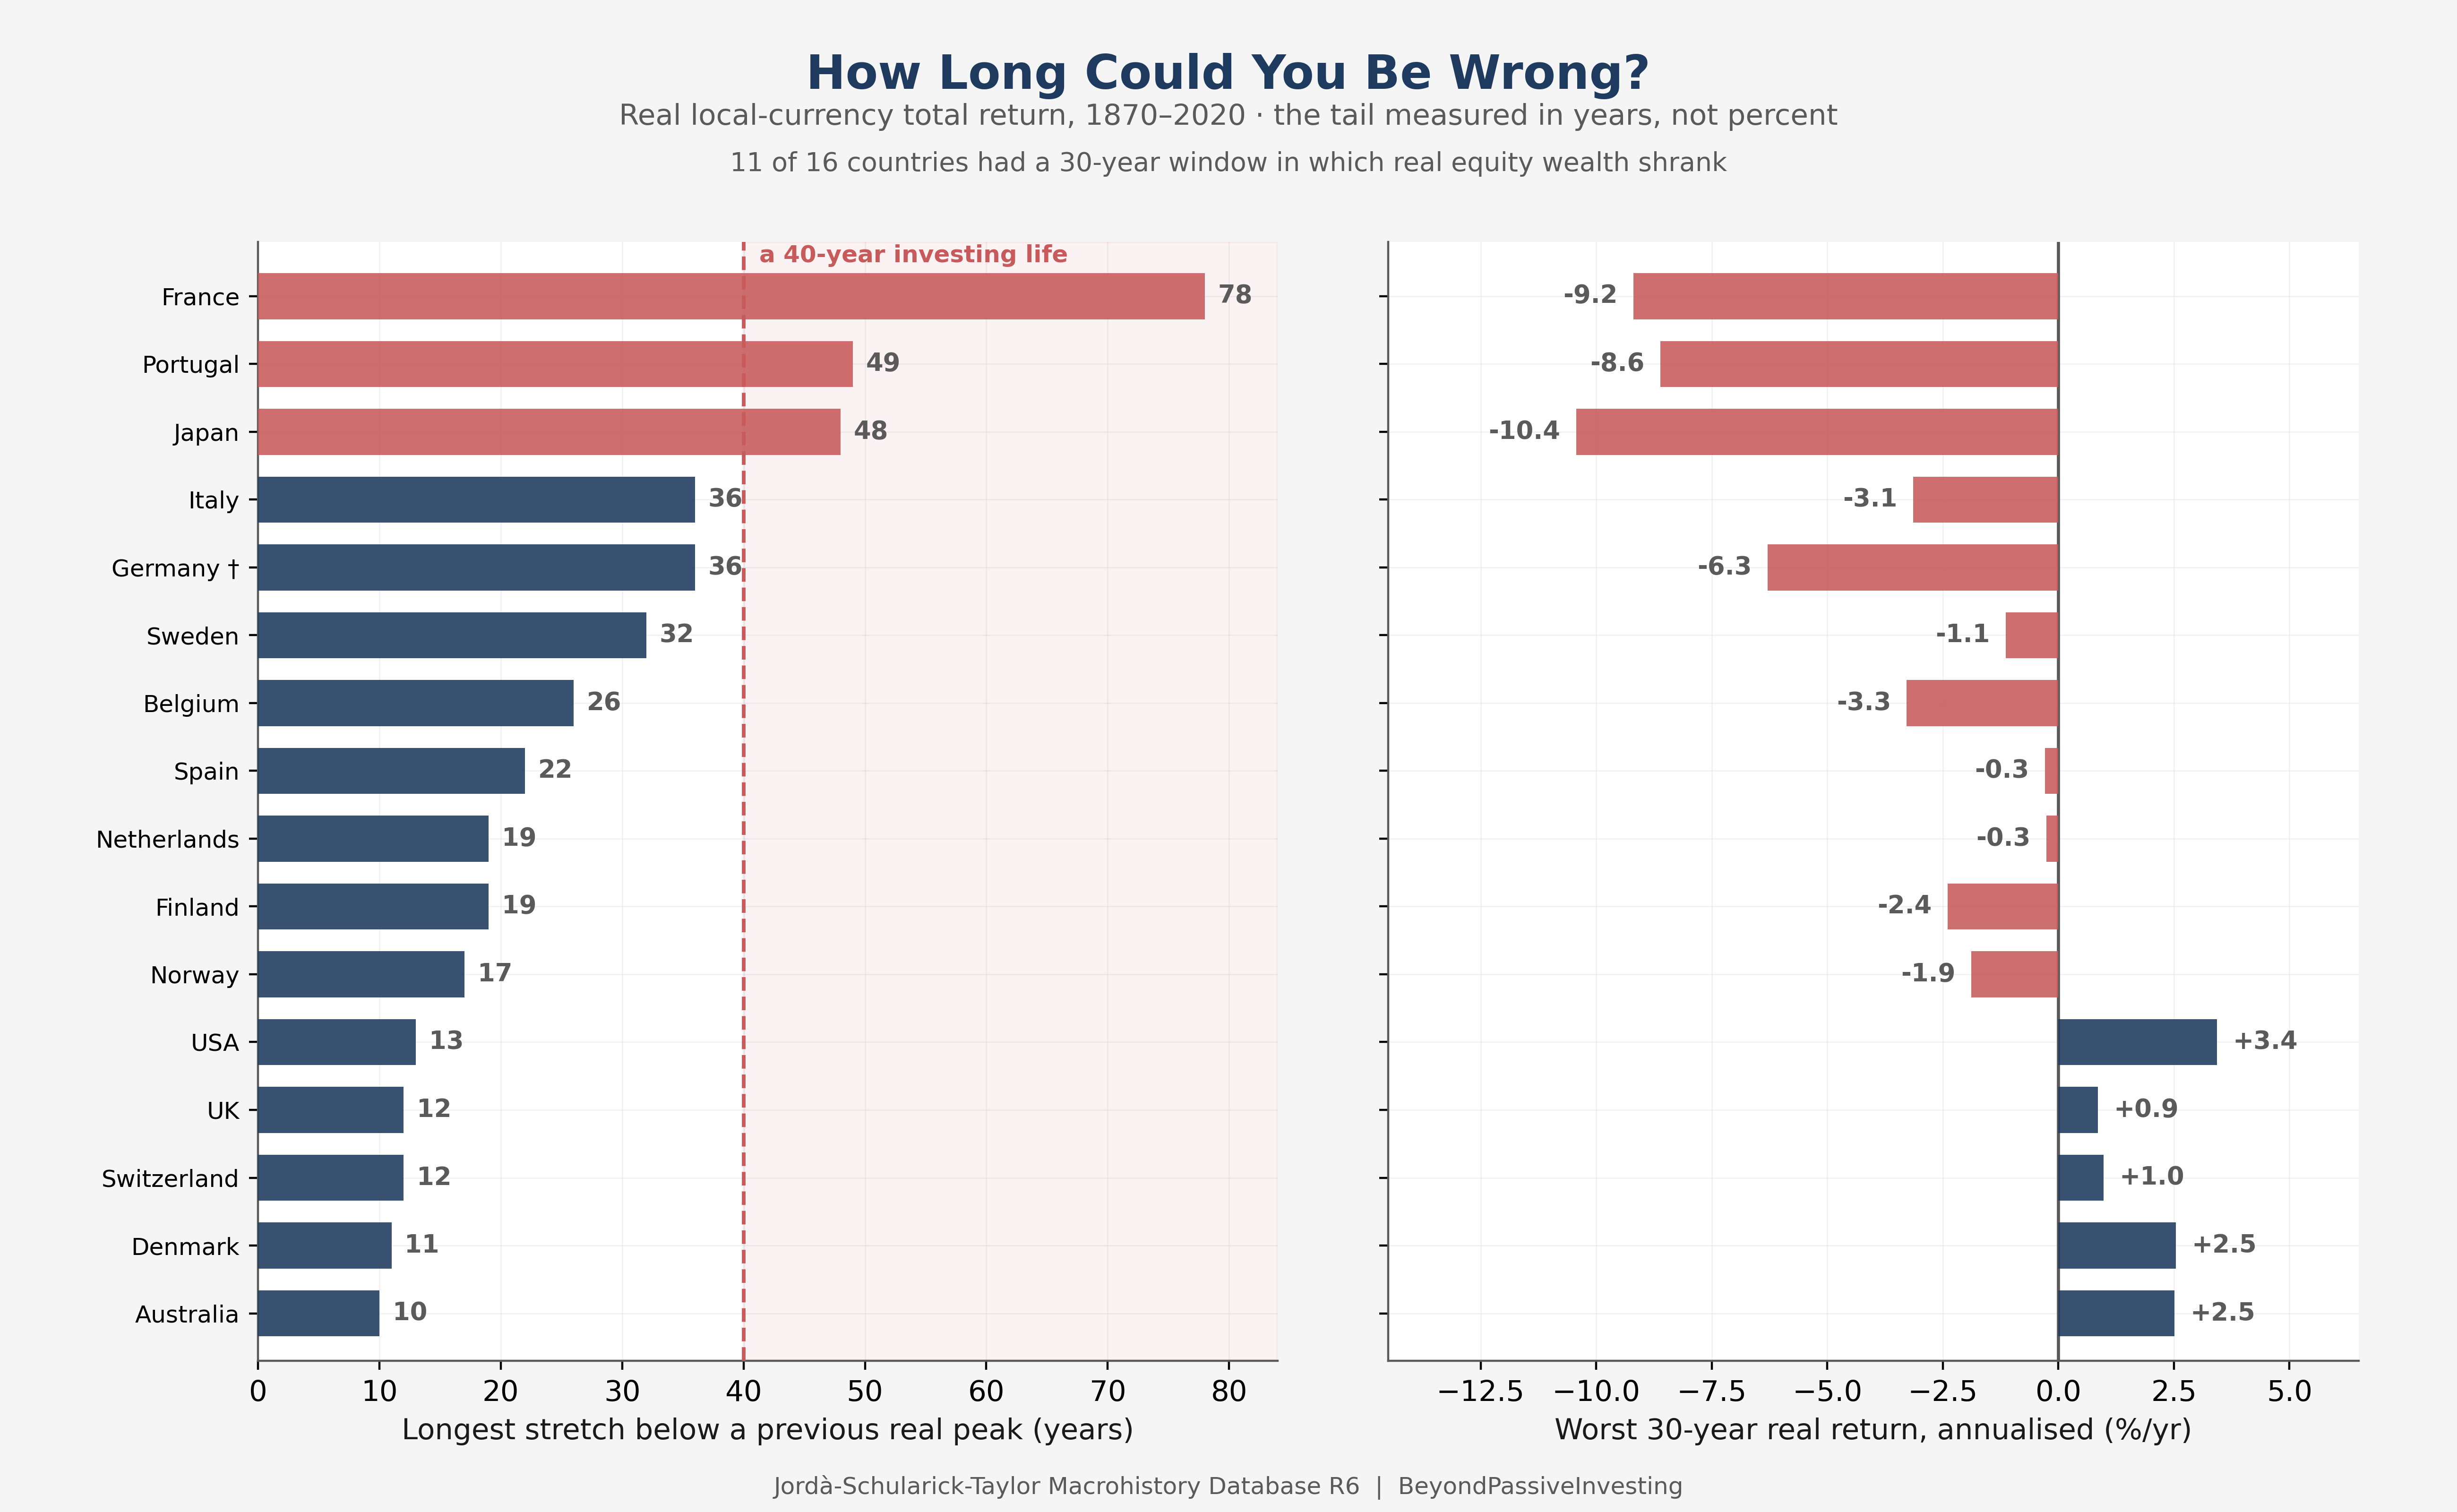
France reached a real peak in 1942 and had not recovered it by 2020. Seventy-eight years, in a G7 country with no hyperinflation, an exchange that stayed open and no expropriation. It simply did not deliver. Eleven of the sixteen markets had a thirty-year window in which real equity wealth shrank. Five did not, and being one of those five is what people mean when they say stocks always win in the long run.
Germany carries a mark in that chart. Its series spans the 1923 inflation and the 1948 currency reform, and at both breaks the recorded numbers measure the unit of account as much as the investment. How the 1948 figure divides between redenomination and genuine loss is still argued over by economic historians and is not settled here. Germany is the most extreme entry in the sample and the least certain, so every result below was re-run without it. Nothing changes: ten of the remaining fifteen markets still had a losing thirty-year window, and the same five never did.
You could not have known in advance
The obvious objection is that France and Portugal were visibly poor bets and the United States visibly a good one, so the dispersion is hindsight rather than risk anyone carried. Japan answers that. By the late 1980s it had led the developed world on trailing long-horizon returns for most of two decades, and the case for owning it was not a story but an arithmetic record longer than most careers. An investor who found that persuasive at the end of 1989 was following exactly the reasoning that today points at the United States.
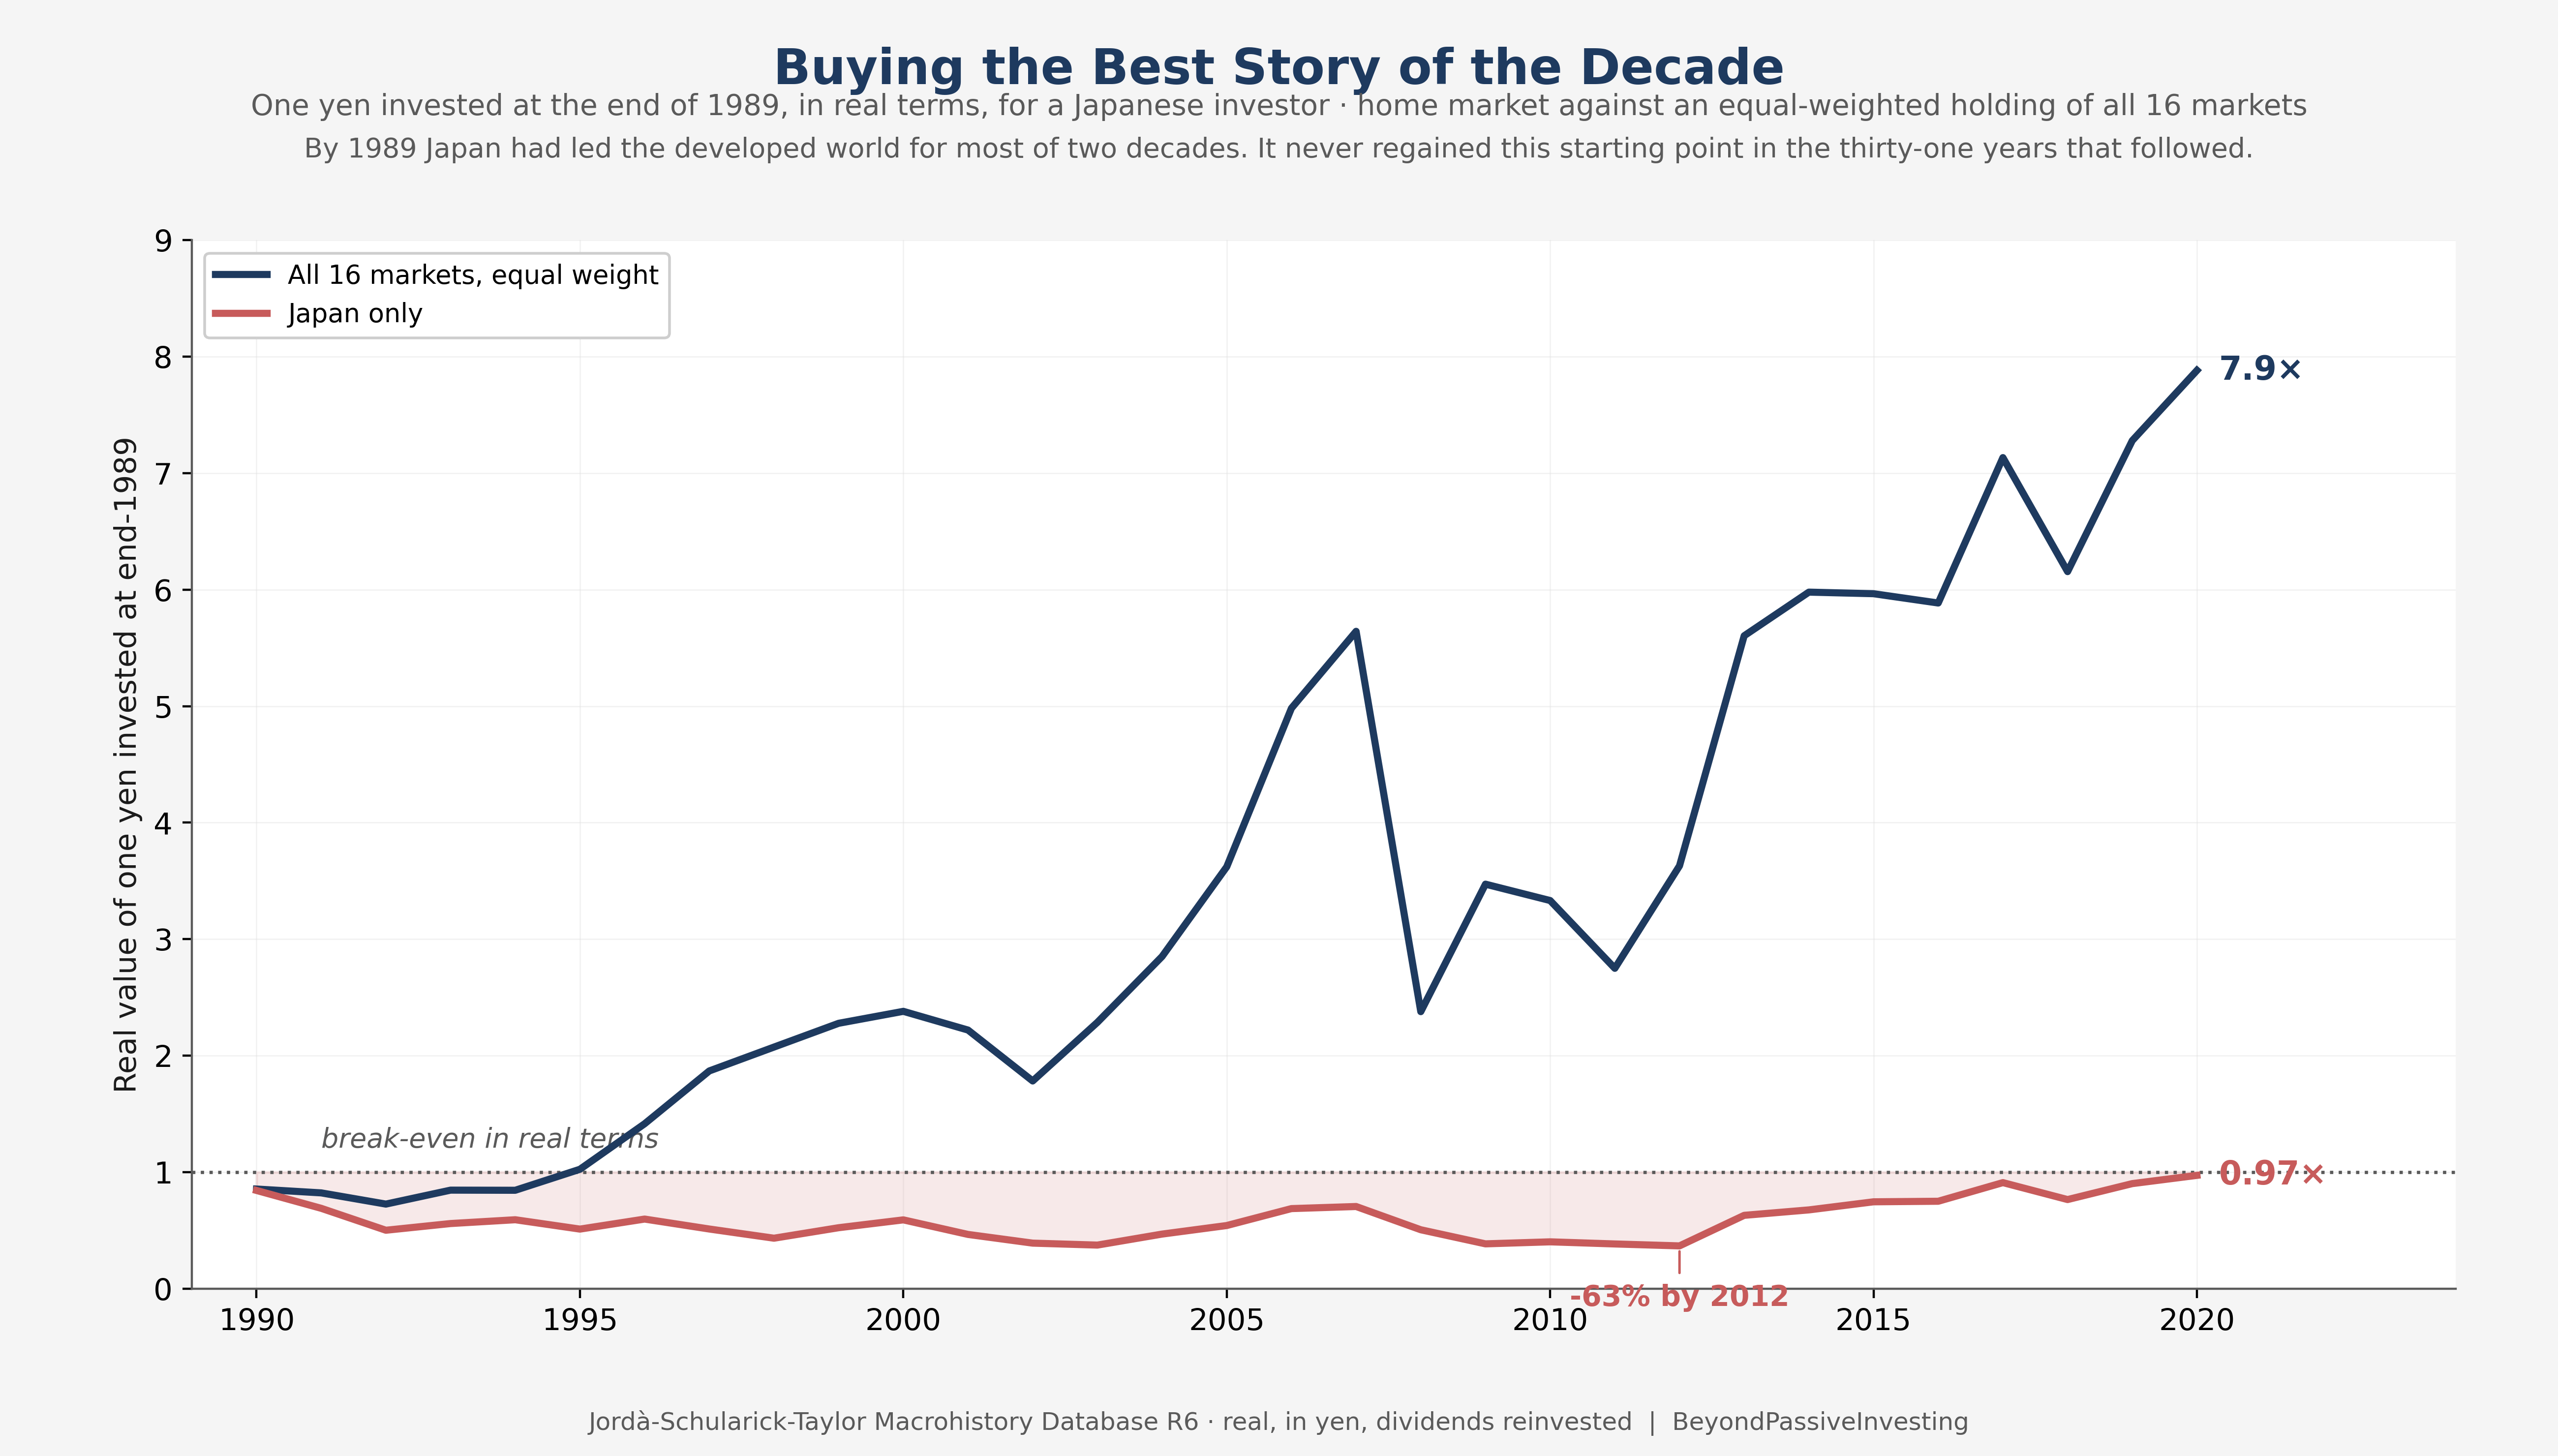
He never got his money back. Not in thirty-one years, not in a single closing year, and at the low he was down by nearly two thirds in real terms. The same yen spread across sixteen markets multiplied almost eightfold over the same span. Being wrong about one country is not a bad quarter; it is the whole of an investing life, and the evidence available beforehand pointed the wrong way.
The countries that are not in the data
Sixteen markets with continuous data since 1870 are sixteen survivors. Russia had a stock exchange in 1917 and China had one in 1949; foreign shareholders were expropriated to zero in both. Argentina was among the largest markets in the world in 1900. Austria-Hungary stopped existing. None of them appear above, because a destroyed market generates no continuous series. Anarkulova, Cederburg and O’Doherty assembled thirty-nine developed markets since 1841 specifically to escape this bias, and put the chance that a diversified thirty-year investor finishes behind inflation at roughly one in eight. The tails below are the optimistic version.
Asking the question the way an investor lives it
Everything so far compares countries. The decision a person faces is different: hold the home market, or hold everything. Answering that honestly means building the comparison the way the money is held and spent, and the usual treatment cheats in three places.
Currency first. A German who buys Japanese equities owns yen exposure whether she wants it or not, and quoting the world portfolio in dollars silently assumes an American holder. There is no return of the world portfolio; there is only the return to a particular investor who holds it. Inflation second. That German consumes in Germany at German prices, so hers is the only deflator describing her experience. The rebalance third: equal weight has to be restored each year, which sells what has risen and buys what has fallen, and over a century and a half that discipline is part of what the portfolio delivers.
So: take each market’s return in its own currency, convert at the actual exchange rate, hold all sixteen equally weighted and rebalanced annually, leave the currency exposure unhedged because that is what a plain global fund gives you, then convert into one investor’s currency and deflate by his cost of living. Change the investor and the holding does not change. Only the money it is measured in does.
The same portfolio, four different lives
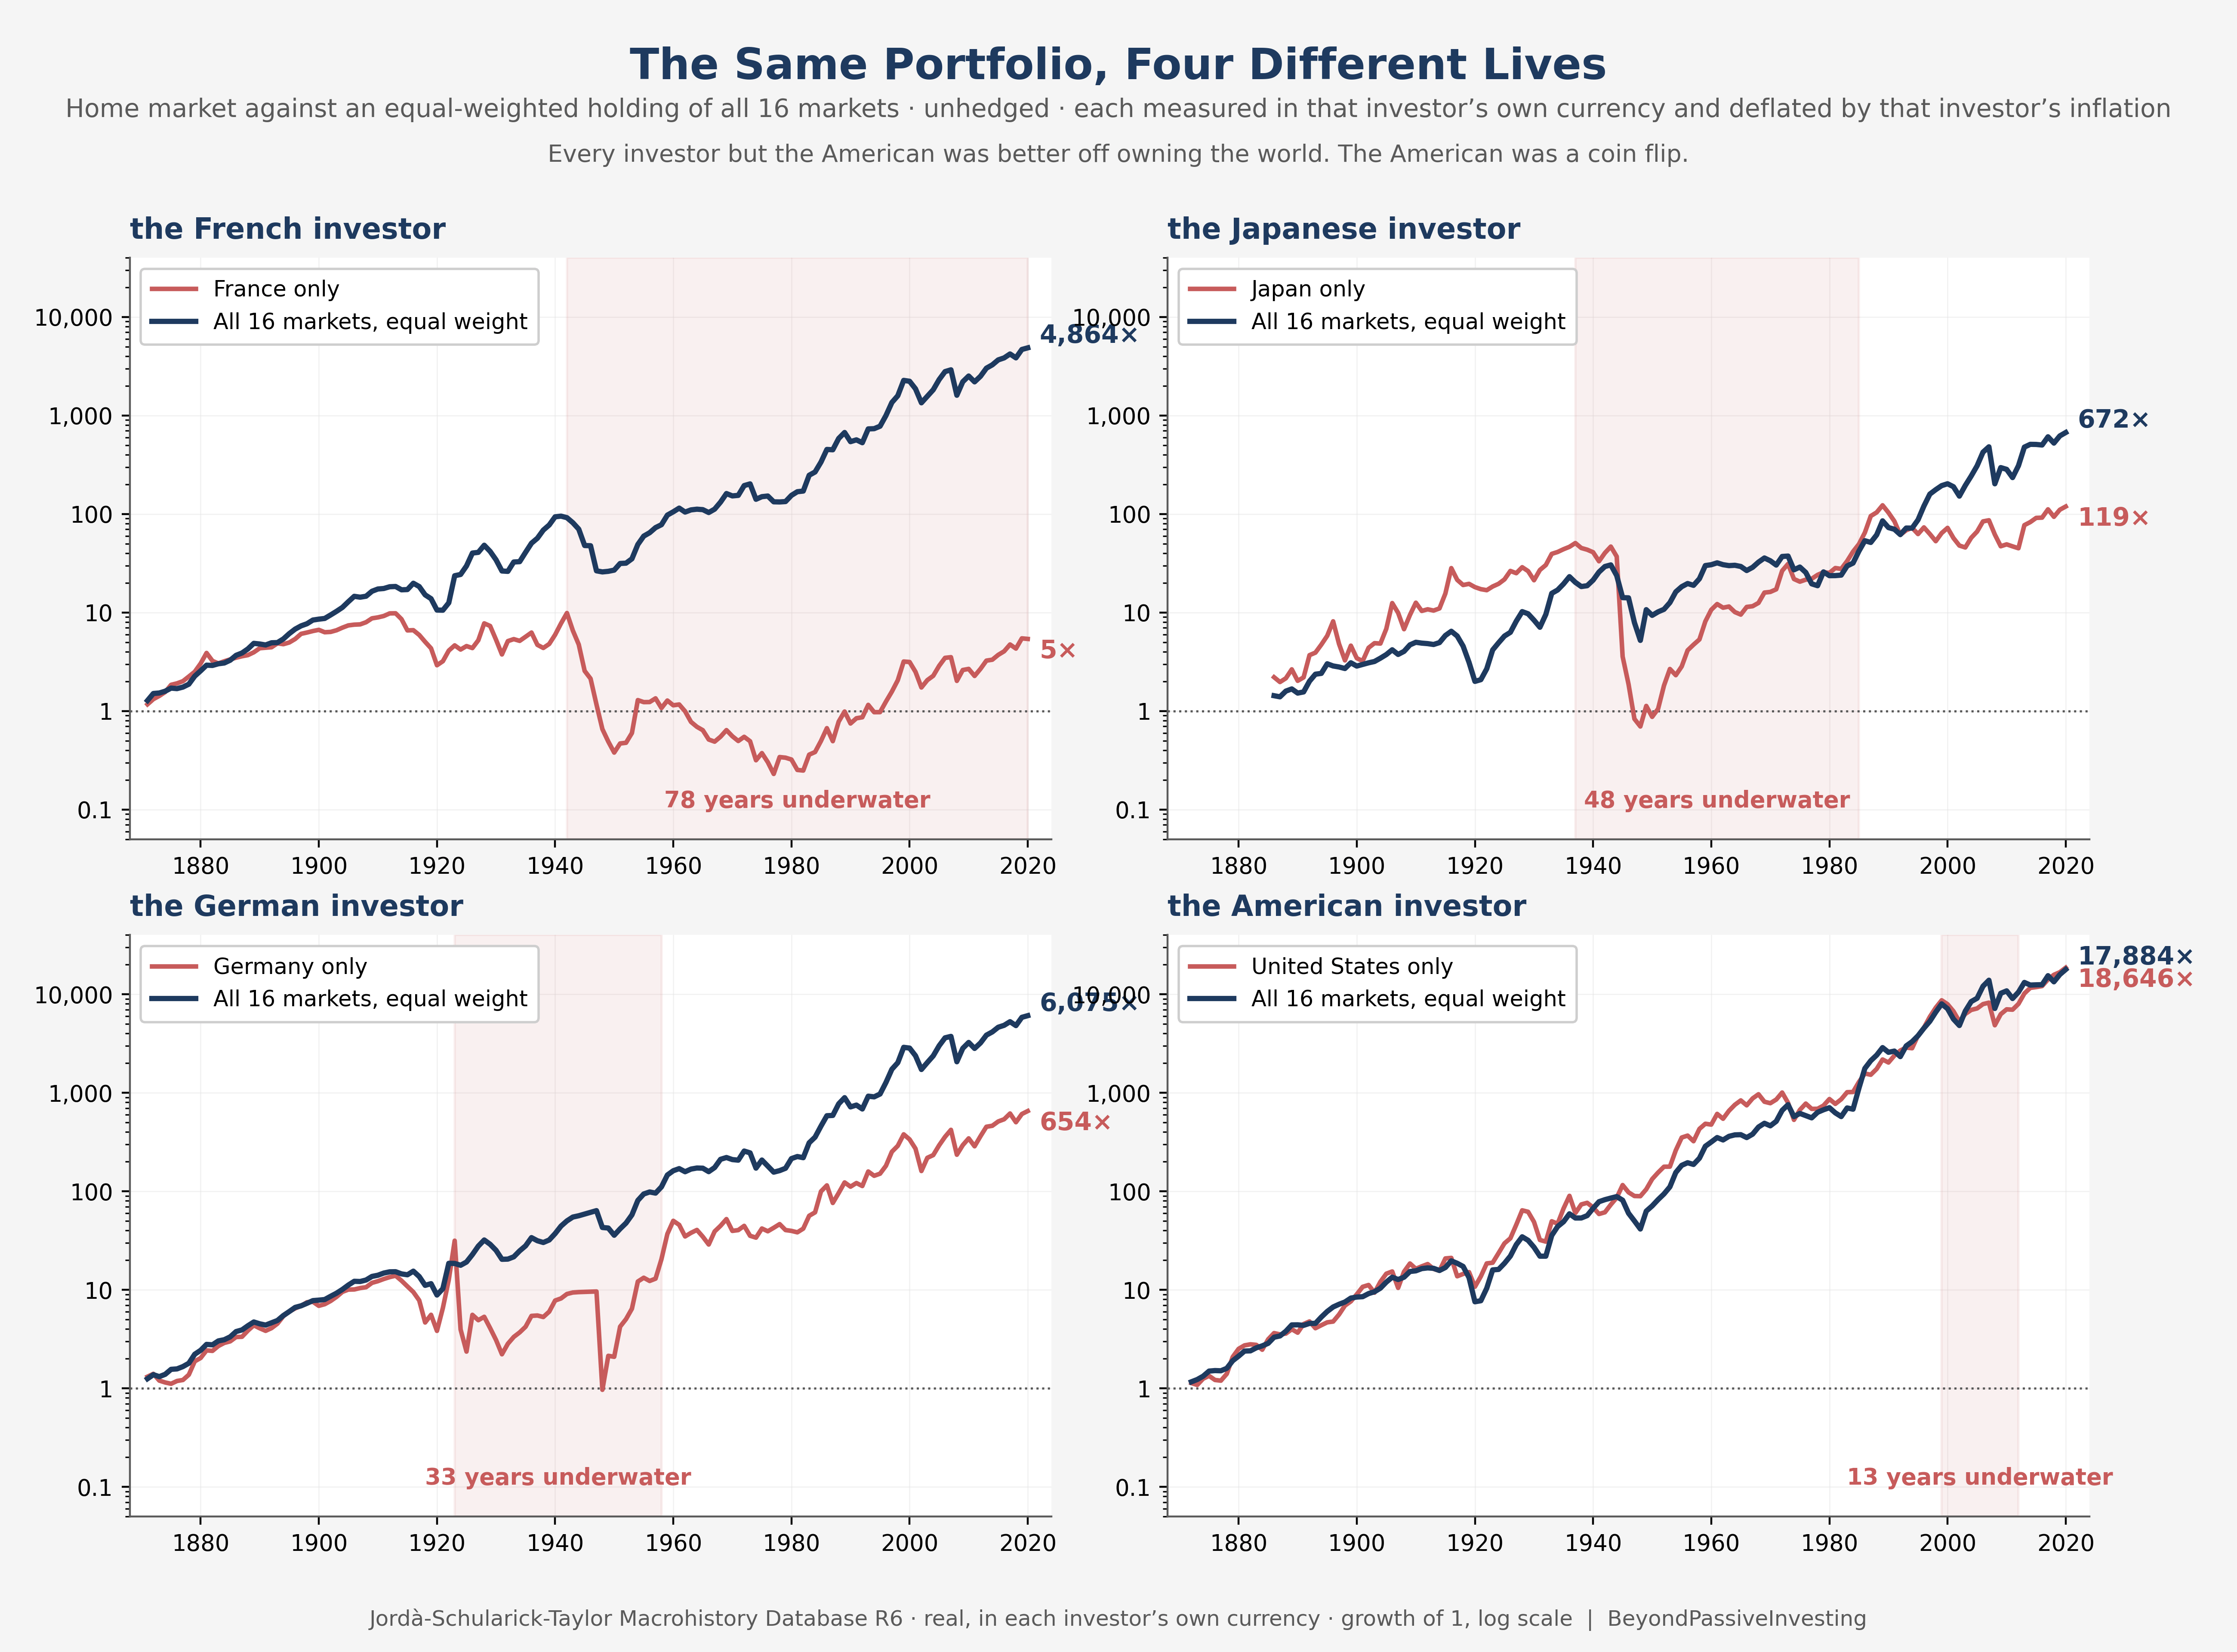
The French investor is the clearest case. Her home market turned one franc into five and spent seventy-eight years underwater. The same period, holding the world and spending in France, is a different asset class in everything but name, and the only thing separating them is that one of them was not a bet on France. Japan shows the same shape, Germany a milder version of it.
The American is the one that matters for honesty. Home and world are indistinguishable: the same return, slightly less time underwater, a slightly worse thirty-year tail. For an American, over this record, diversification was free and it was also pointless. Every other investor was paid to hold it.
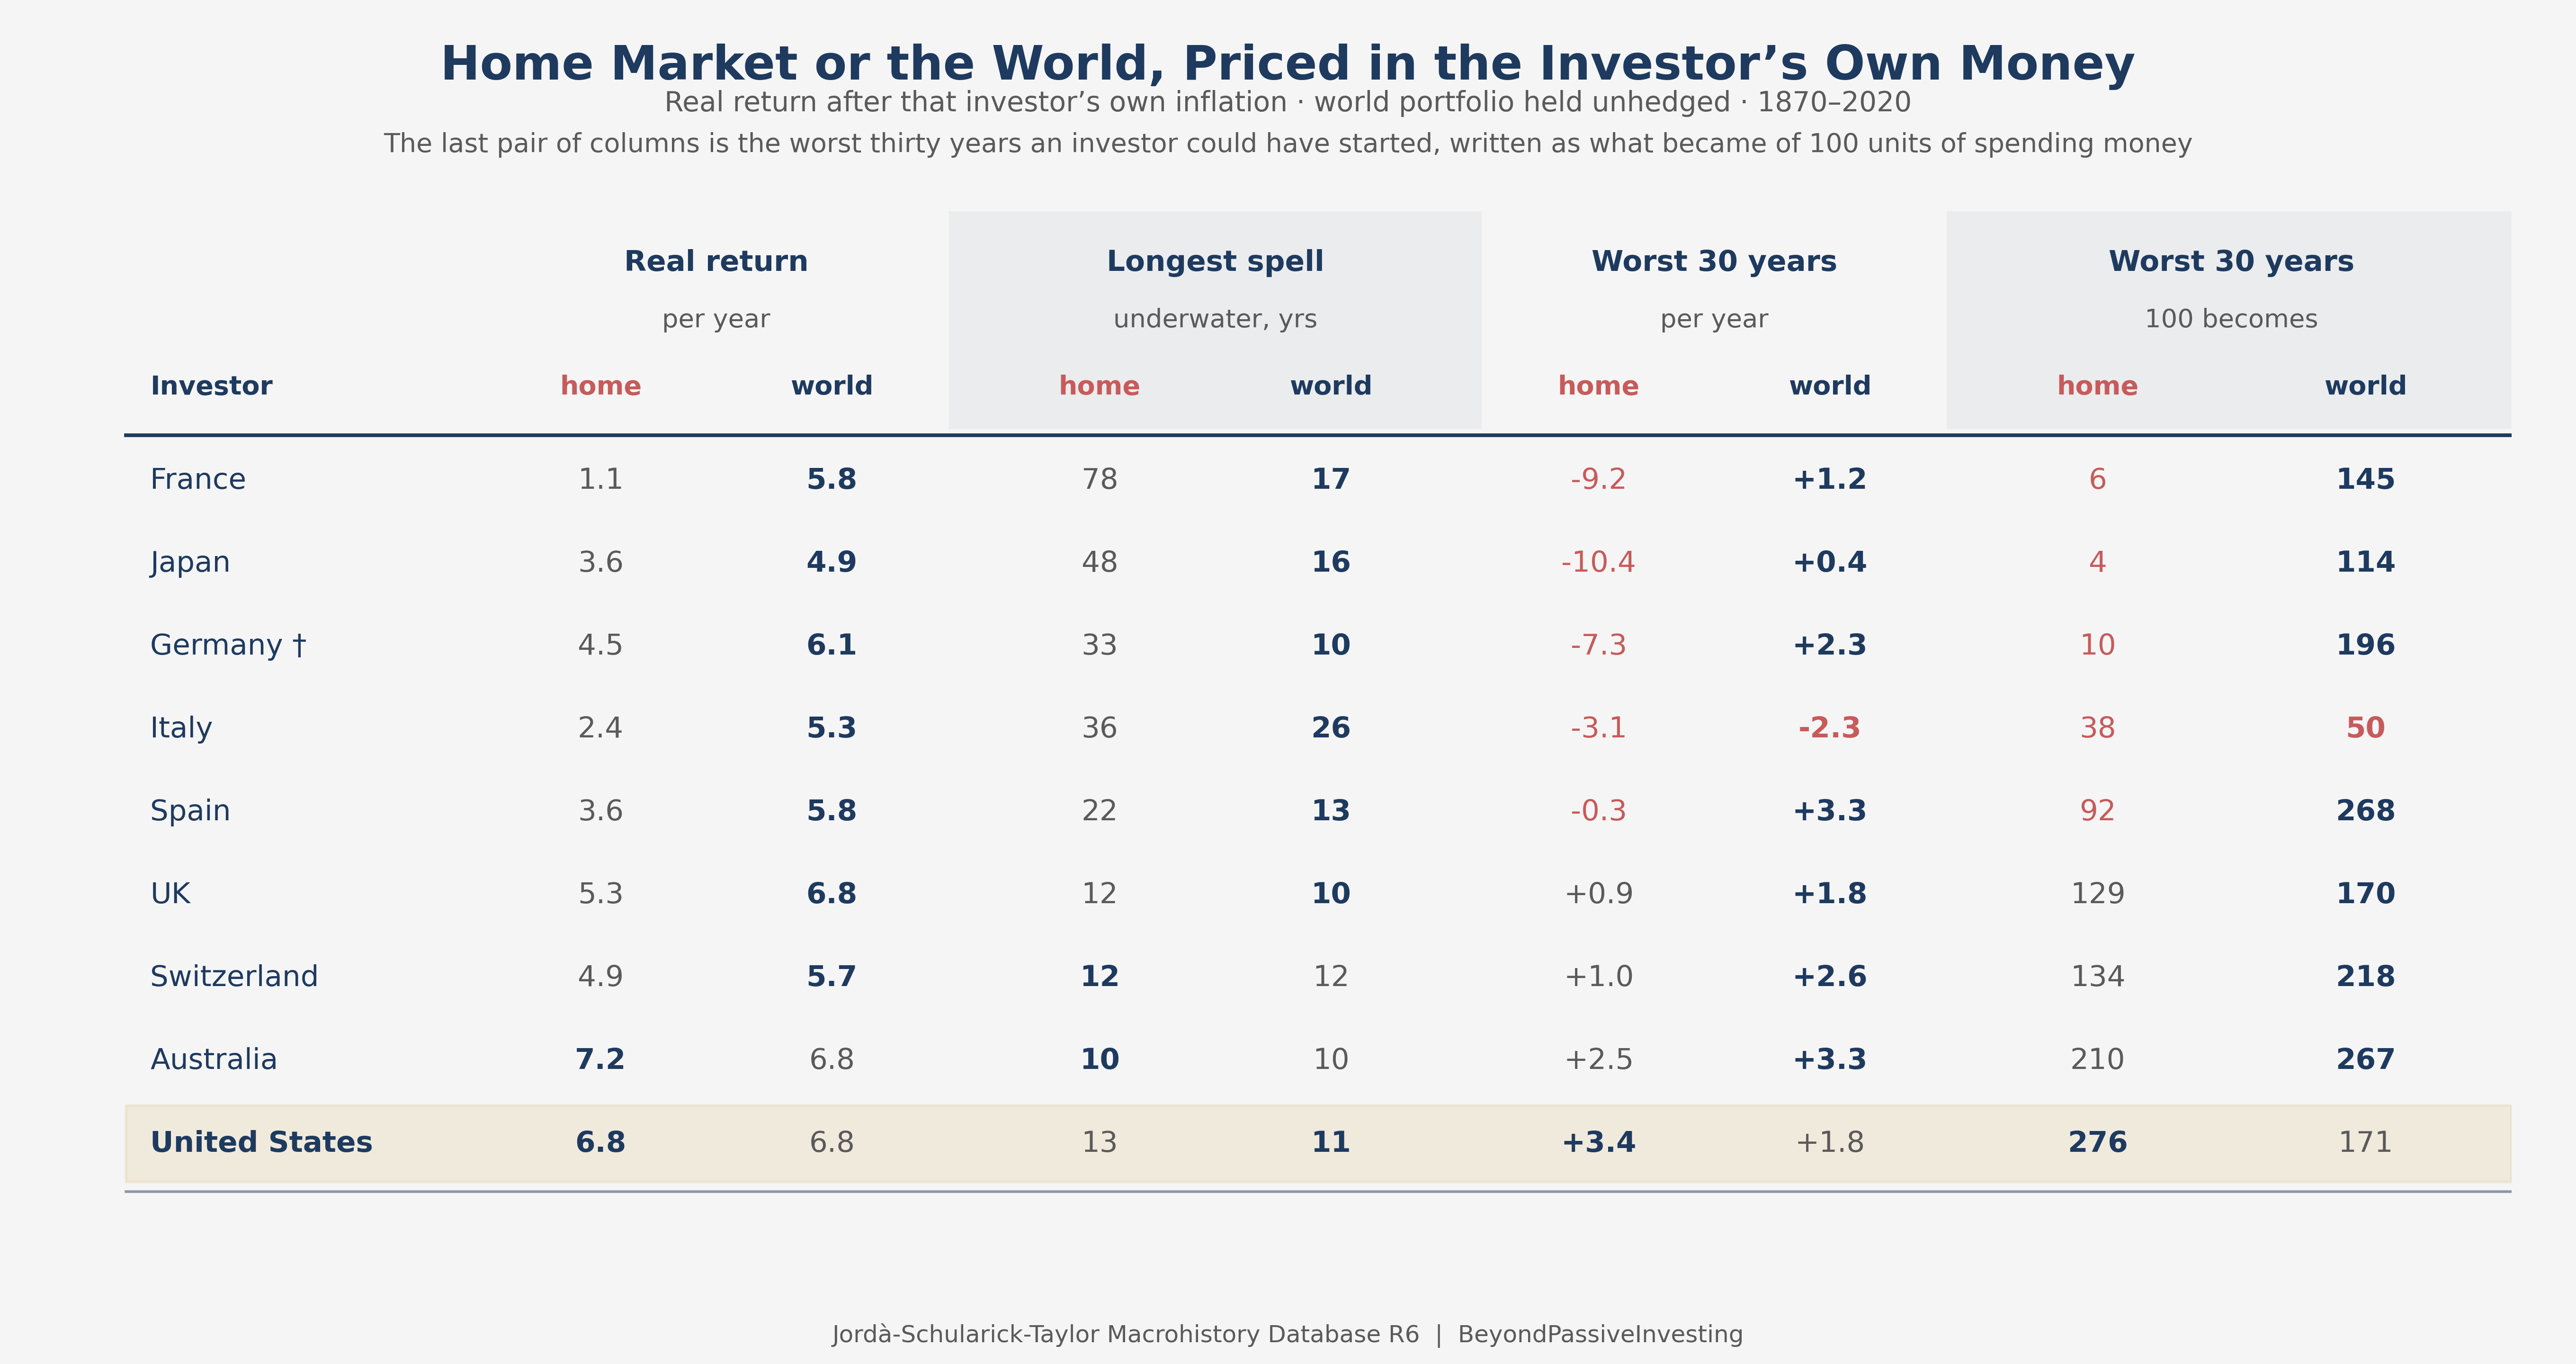
Read the last pair of columns first, because a rate quoted per year hides what it does to money. They take the worst thirty-year stretch in each row and ask what became of a hundred units of purchasing power. In France and Japan the home investor was left with almost nothing and the diversified one was left whole. That is not a difference in a risk statistic. One of them is a retirement and the other is not.
Easier to miss: the world portfolio is the same holding in every row, and its real return barely moves across nine investors and a century and a half of divergent monetary histories. The home markets in the same column span a factor of seven. Where you live determines almost nothing about the outcome of the diversified portfolio and almost everything about the concentrated one.
Does this survive the wars?
A result leaning on 1919 to 1949 deserves suspicion. The exchange rates recorded for the war-disrupted currencies in those years are administrative rather than traded, and capital controls made repatriation impossible anyway. Taken literally the data implies a real exchange-rate move of nearly a thousand percent for Italy in 1942, so such moves are capped; the cap binds nowhere outside those two windows. The stronger test is to discard the contaminated years altogether.
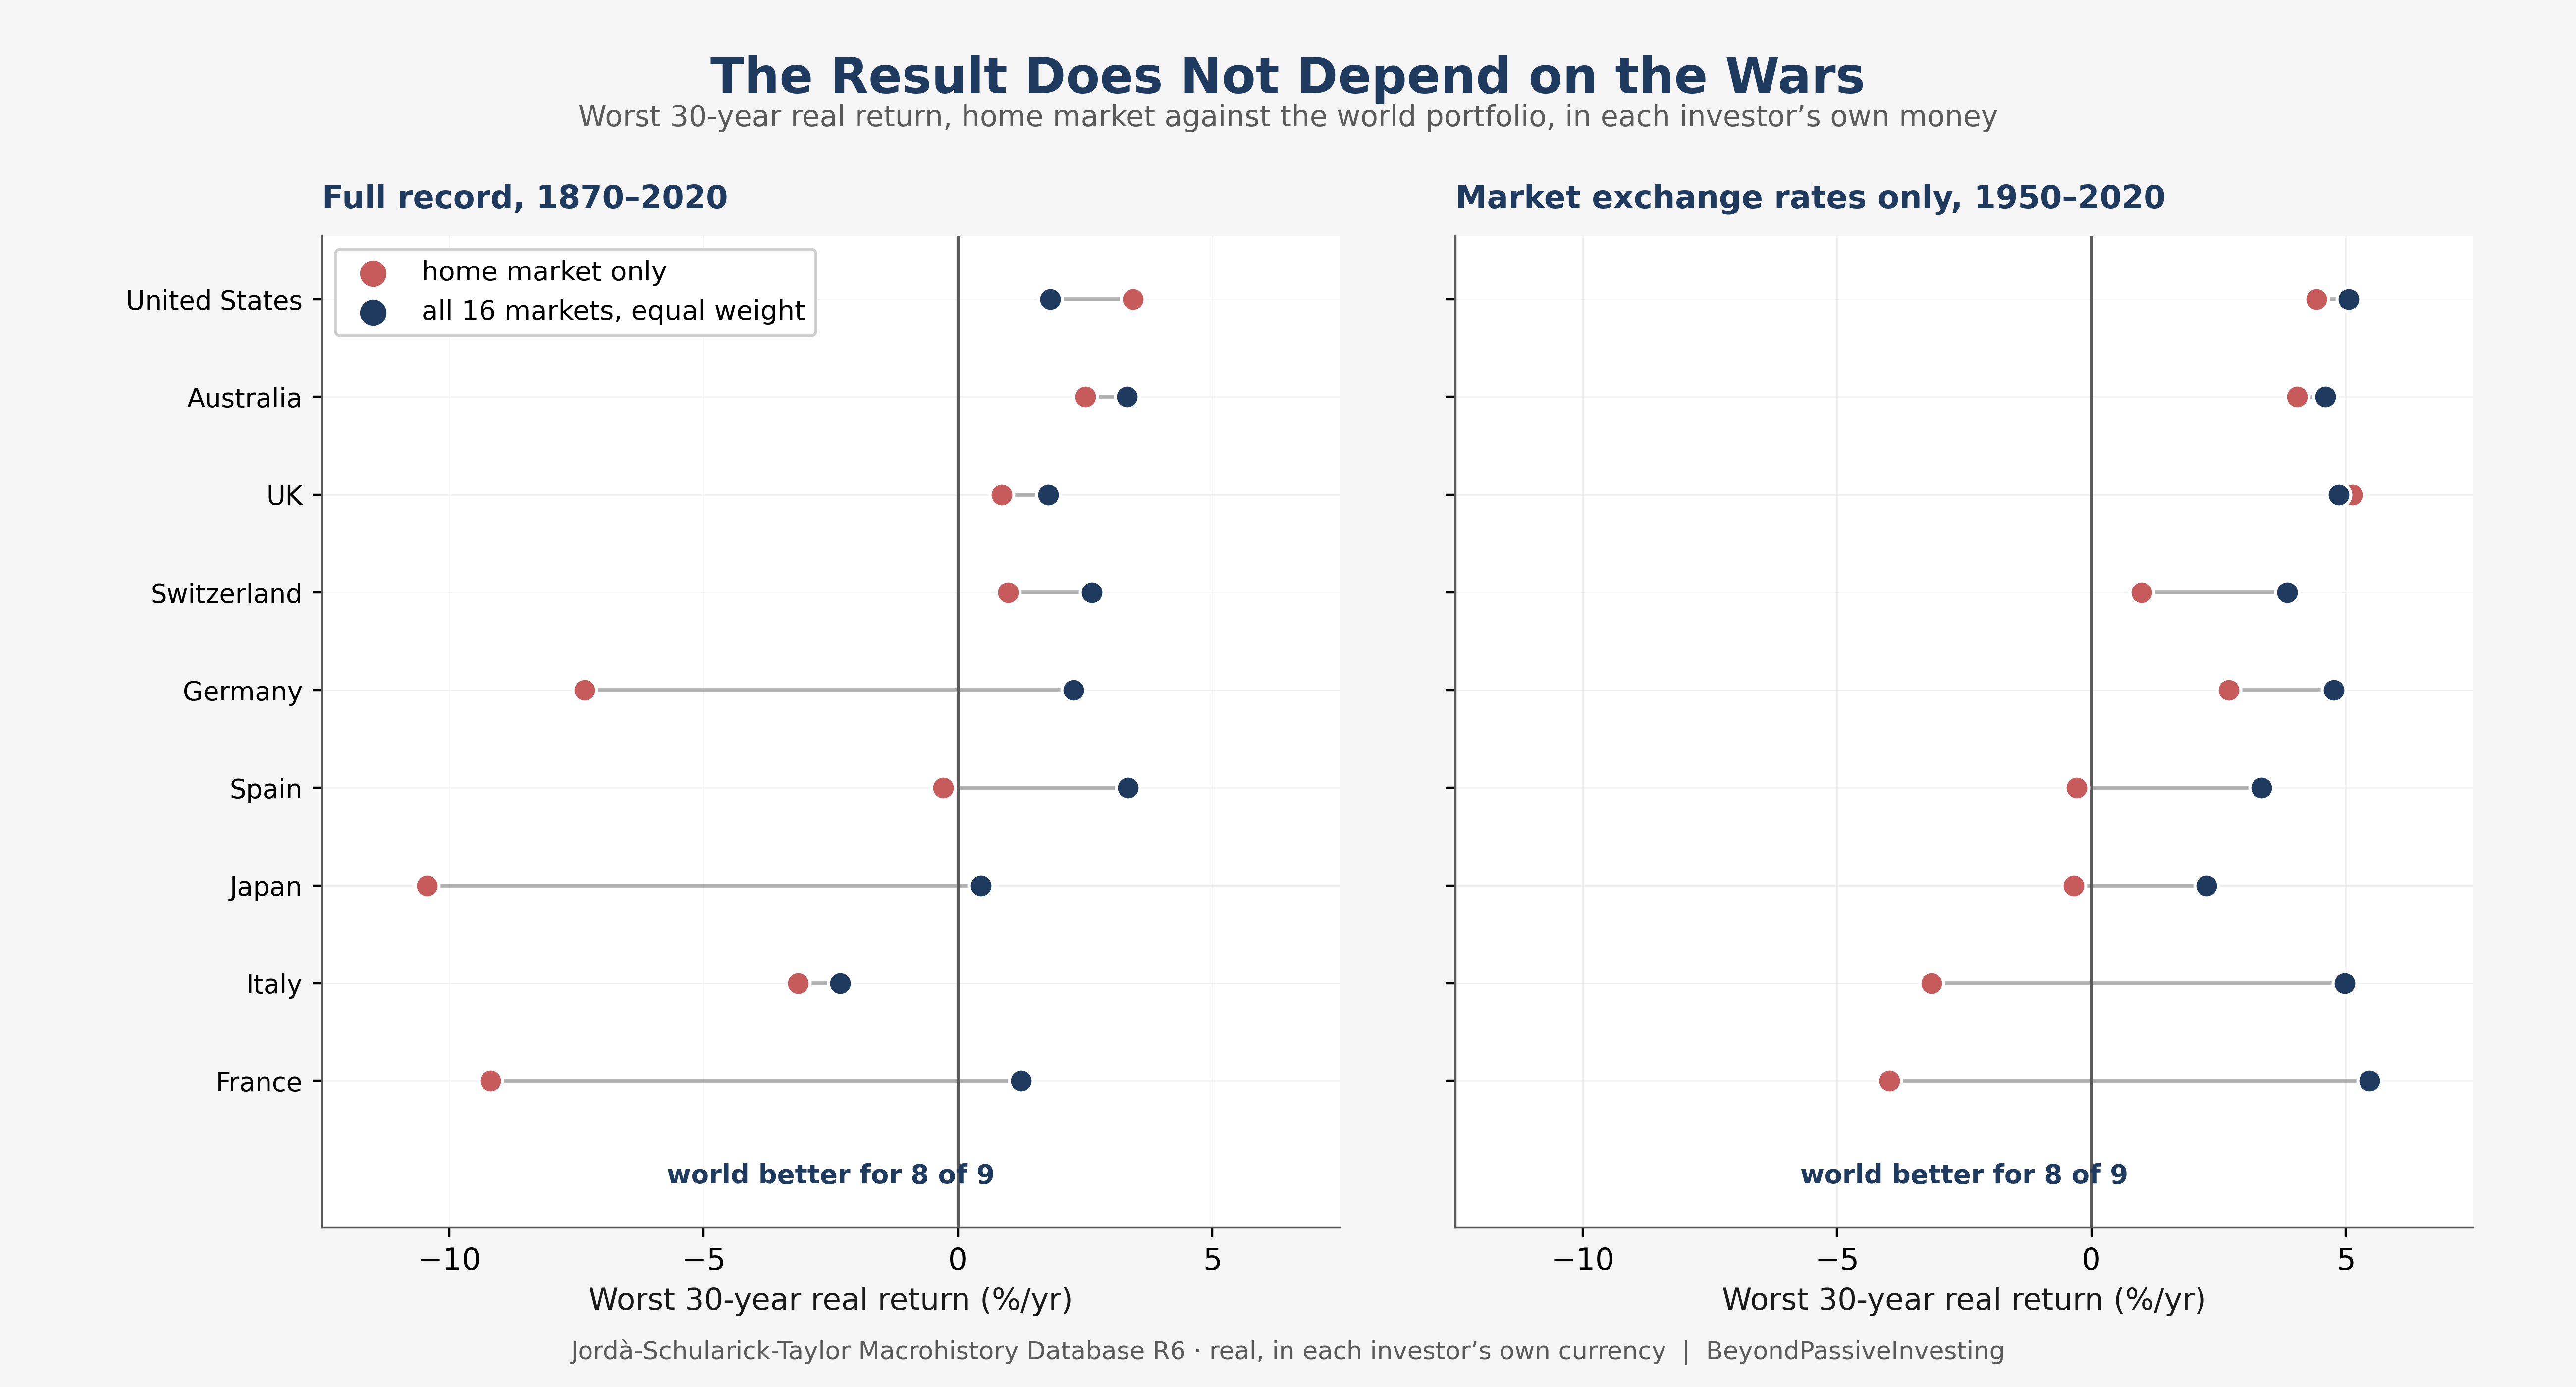
The result gets stronger. Restricted to 1950 onward, where every rate is a market rate, the world portfolio produced a better worst thirty years than the home market for eight of the nine investors, the exception being the United Kingdom by three tenths of a point. Even the American, who had no advantage over the full record, gains. Whatever is happening here, the world wars are not driving it.
The recent record makes this harder to hear
None of this says the United States is about to become an ordinary country, and recent evidence points the other way. From the financial crisis to 2024 American equities beat almost everything, and a European who diversified spent fifteen years being paid to regret it. The concentration this produced is not subtle: the United States is now about sixty-four percent of the all-country world index against roughly a quarter of world output. Then 2025 reversed hard, international equities beating the S&P 500 by the widest margin since 1993, mostly on a weaker dollar.
One year settles nothing, and that is the point. Fifteen years of American outperformance is about the weight of evidence that pointed at Japan in the mid-1980s. The argument here is not that American equities are expensive. It is that the evidence people find persuasive is far shorter than the mistakes the record contains.
What this leaves
Home bias is a concentrated position in a draw nobody made. For eleven of sixteen developed markets it produced a thirty-year window of real losses, and for four of them a stretch of underwater decades longer than the working life of the person holding it. Spread across all sixteen and measured in the investor’s own money, the outcome becomes roughly the same wherever he happens to live.
Two things this does not establish. It does not establish protection against a global crash, because there is none: the world portfolio fell by more than half in the early 1920s and fell hard in 1929, 1974 and 2008, when equity risk arrived everywhere at once. Asness, Israelov and Liew put the same point the other way up, and theirs is the more useful direction: markets crash together over months and diverge over decades, so the diversification that fails in a panic is the one that works over a lifetime. Spreading a single asset class across more countries removes country risk and leaves the asset class intact.
Nor does it establish what to hold today. Equal weighting sixteen developed markets is a research construction, not a portfolio, and the index most readers own is neither equally weighted nor especially diversified. That question needs real market capitalisations, daily data and an accounting of costs.
What the long record settles is narrower. The average return everyone quotes was never available to anybody, the dispersion around it is wide enough to swallow a career, and for every investor here except the American, the country of birth mattered more than any other allocation decision available to him.
Data notes
Real returns deflate the nominal return directly, never truncating it first. Closed exchanges — Japan in 1946 and 1947 — carry a zero nominal return, so the inflation of those years still bites. Series begin between 1871 and 1900, so every cross-country ranking here uses the common 1900–2020 window. Administrative exchange rates in 1919–23 and 1942–49 are capped at thirty-five percent a year in real terms and bind nowhere else. German figures spanning the June 1948 currency reform mix Reichsmark and D-Mark quotations against a controlled-price index; the right treatment is disputed among historians of the period, so Germany is marked wherever it appears and every conclusion was re-run without it. The sixteen countries are survivors, which cannot be corrected for at all.
References and further reading
Anarkulova, A., Cederburg, S. and O’Doherty, M. S. (2022). Stocks for the long run? Evidence from a broad sample of developed markets. Journal of Financial Economics 143(1), 409–433.
Asness, C. S., Israelov, R. and Liew, J. M. (2011). International diversification works (eventually). Financial Analysts Journal 67(3), 24–38.
Buchheim, C. (1988). Die Währungsreform 1948 in Westdeutschland. Vierteljahrshefte für Zeitgeschichte 36(2), 189–231.
Dimson, E., Marsh, P. and Staunton, M. (2002). Triumph of the Optimists: 101 Years of Global Investment Returns. Princeton University Press. Updated annually as the UBS Global Investment Returns Yearbook.
Jordà, Ò., Knoll, K., Kuvshinov, D., Schularick, M. and Taylor, A. M. (2019). The rate of return on everything, 1870–2015. Quarterly Journal of Economics 134(3), 1225–1298. Data: Jordà-Schularick-Taylor Macrohistory Database, release 6, macrohistory.net.
Mehra, R. and Prescott, E. C. (1985). The equity premium: a puzzle. Journal of Monetary Economics 15(2), 145–161.
Peters, O. (2019). The ergodicity problem in economics. Nature Physics 15, 1216–1221.
Peters, O. and Gell-Mann, M. (2016). Evaluating gambles using dynamics. Chaos 26(2), 023103.
Siegel, J. J. (2014). Stocks for the Long Run, 5th edition. McGraw-Hill.
2025 index returns: MSCI EAFE and MSCI ACWI ex-USA calendar-year total returns against the S&P 500, as reported January 2026.
Great article.
I always hated when people believe “All stocks go up in the long term all the time. Look at history” It ignores the realities your article points out.
I love this dataset. There’s just so much you can do with it.