
A reader asked whether the birthplace lottery that decided equity outcomes also decided bond and gold outcomes. It did, and the shape of the answer is different from what the equity article found.
The same measurement applied to bonds
The construction matches the equity article. One unit of currency, invested at home in long government bonds, deflated by the home consumer price index, held from 1870 to 2020. What happened to the purchasing power of a bondholder who never left.
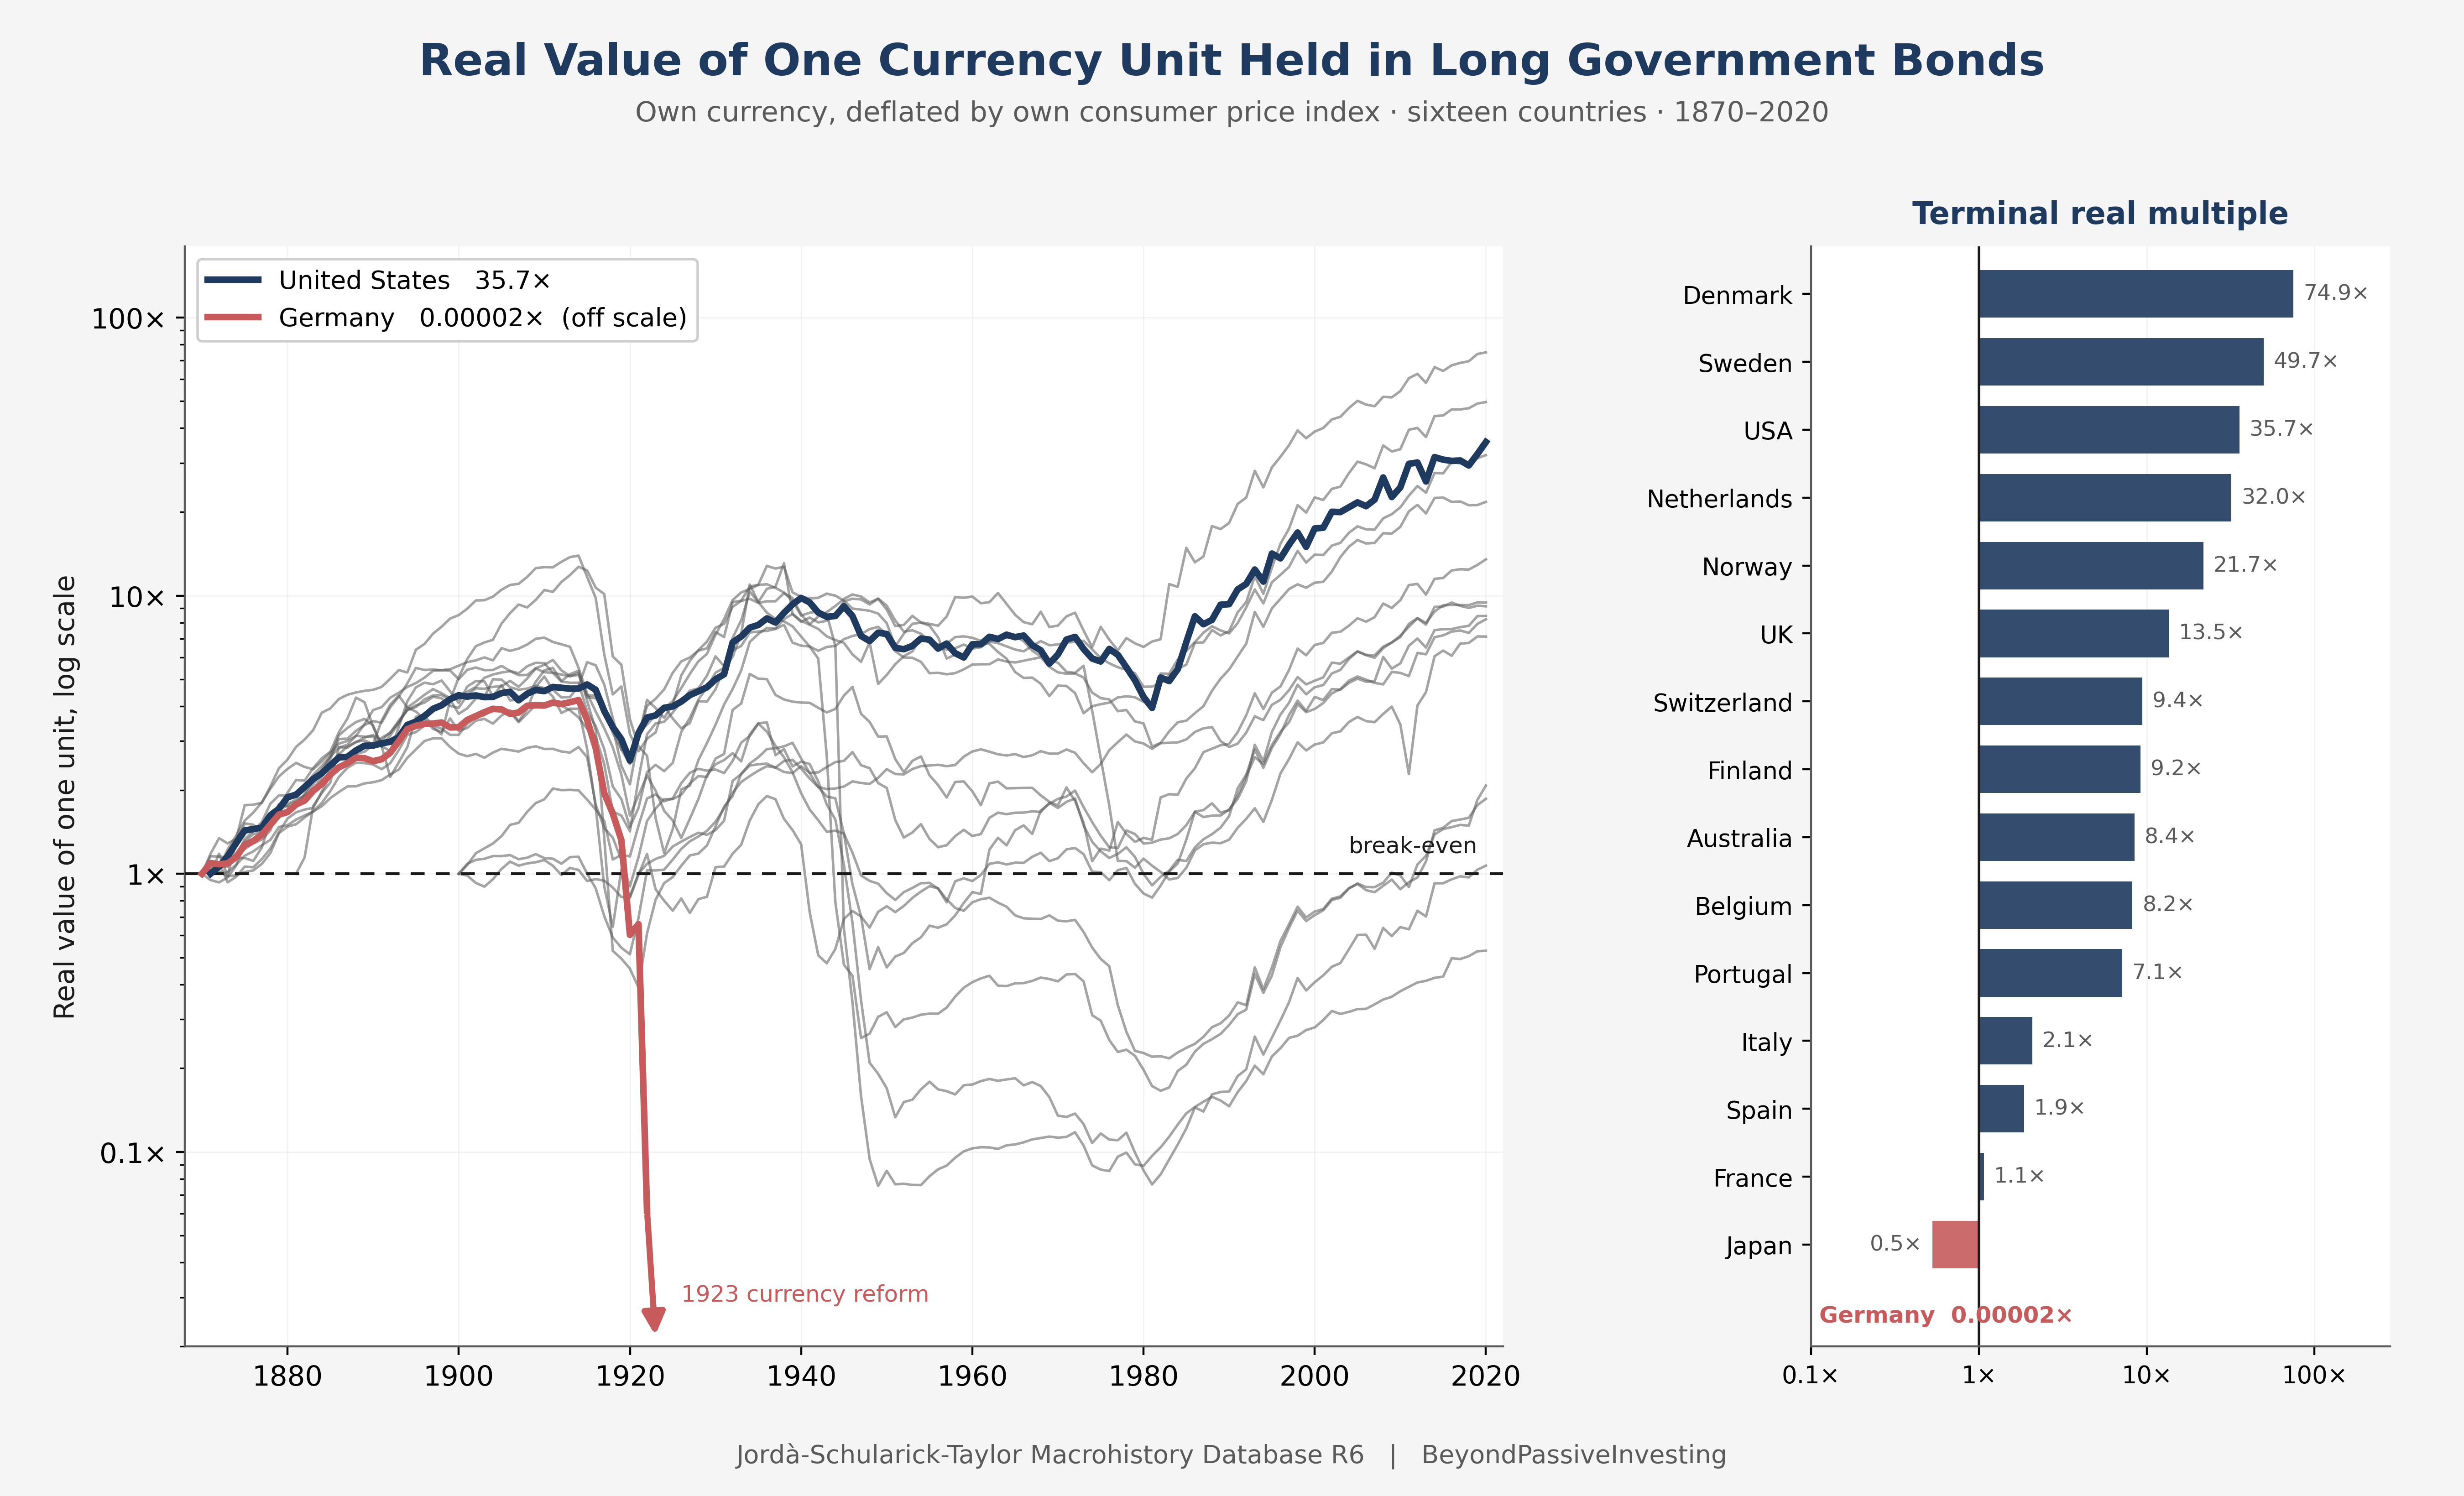
Three of sixteen markets ended below where they started. The German line draws the eye, but France and Japan are the more instructive cases, because neither experienced a hyperinflation. They spent long enough under inflation and yield control that a century and a half of coupons bought nothing.
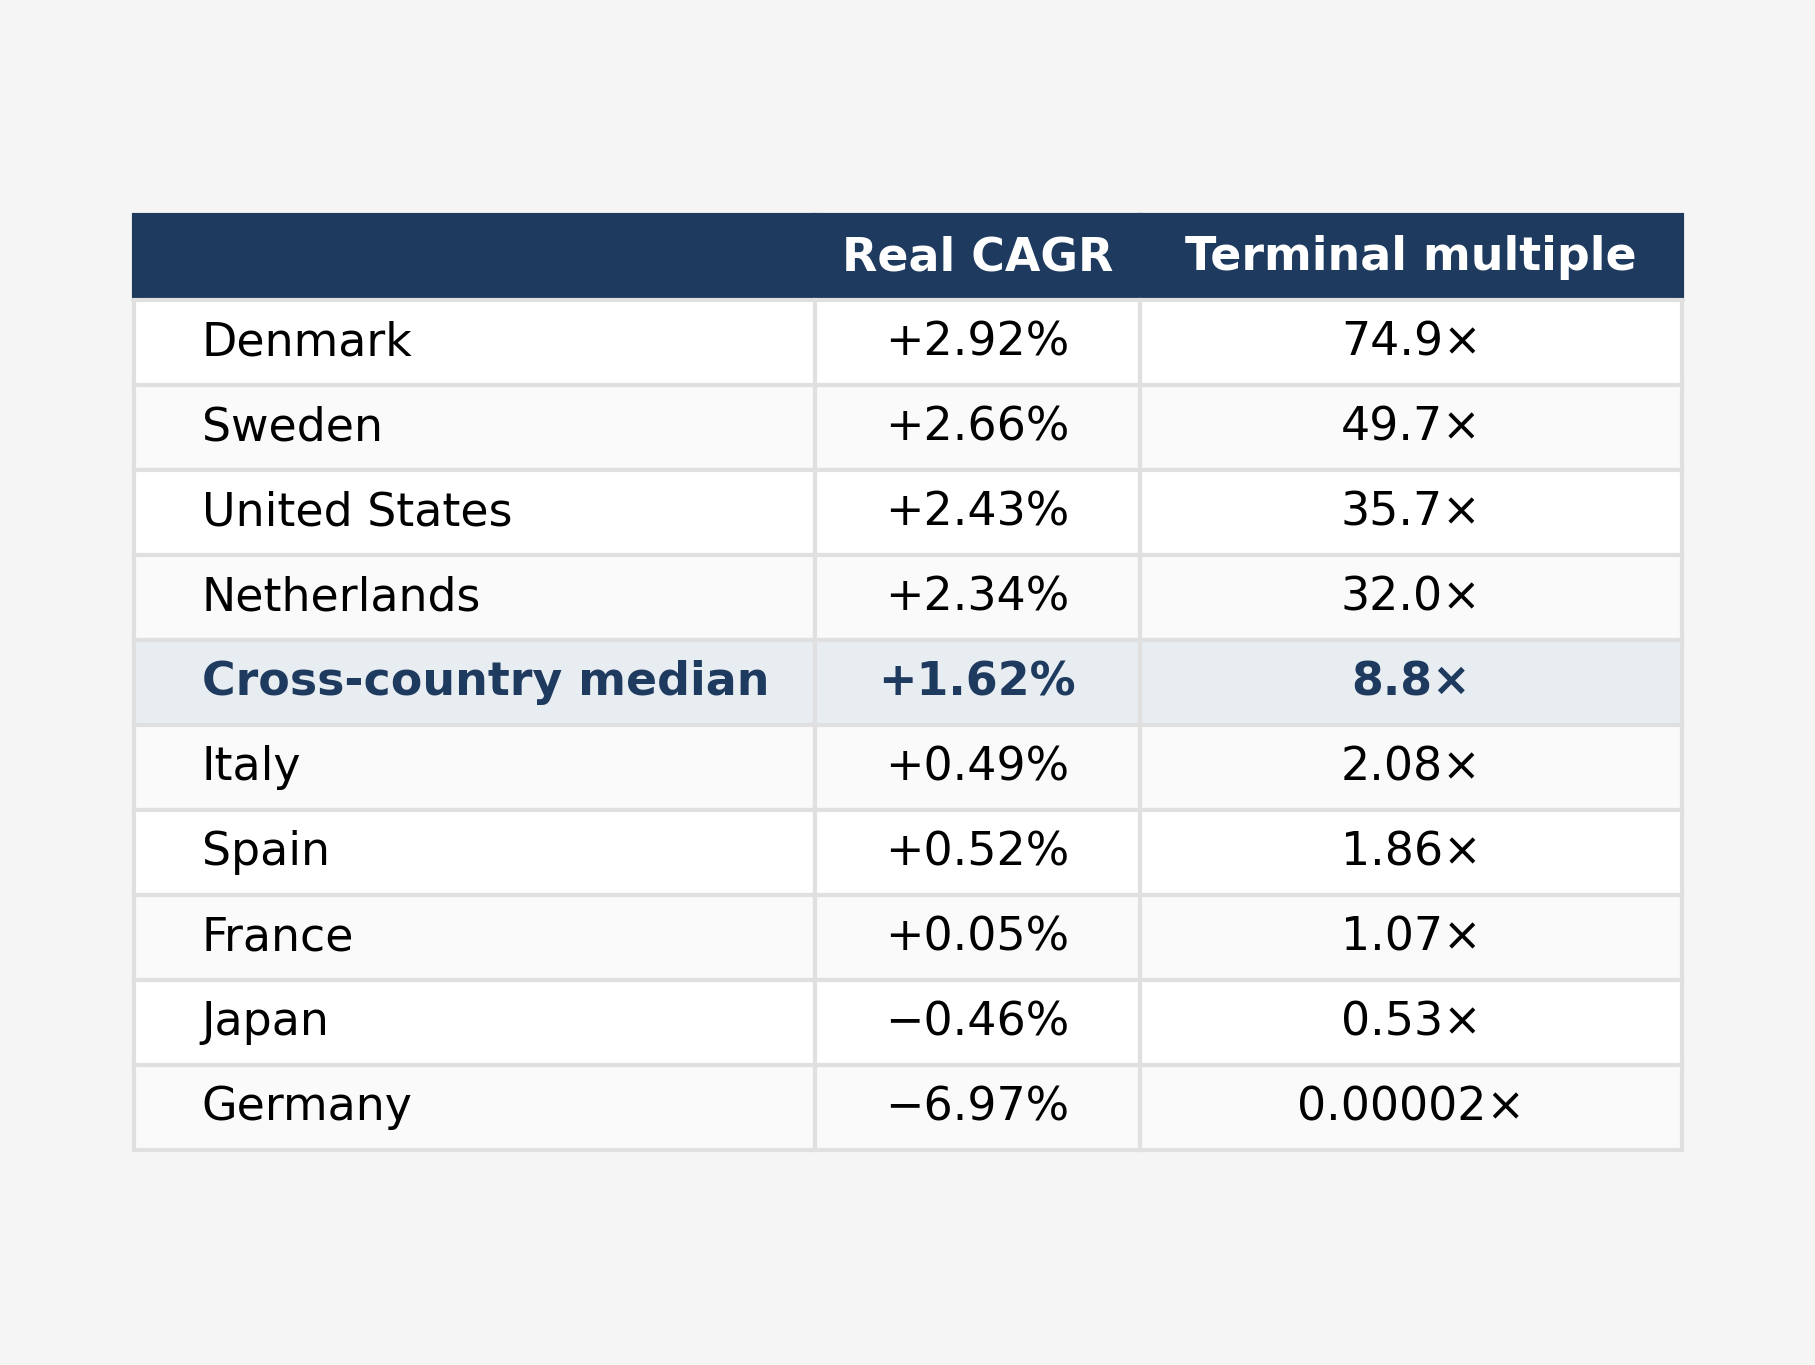
Against equities on the identical construction, the comparison is not the one most people expect. The equity distribution is far wider, from Portugal at 0.73 percent a year to Australia at 7.18. That width was the subject of the last article. What the bond distribution has instead is a floor that gives way. Every equity market in this sample delivered a positive real rate over the full period. Four bond markets did not.
One figure in the chart is softer than it appears. Germany’s exchange was closed from 1944 to 1948 and those years carry a zero nominal return before deflation, which flatters the result. The 1948 currency reform converted Reichsmark bond claims at roughly ten to one, and measured inflation before it was held down by price controls.[1] The German number is a floor rather than an estimate.
The yield at purchase
A bond differs from a share in that the return is contracted at the outset. It is worth asking how much of the eventual outcome that contract determines. The panel answers directly: every country, every starting year, the long yield at purchase against the annualised return over the decade that followed.
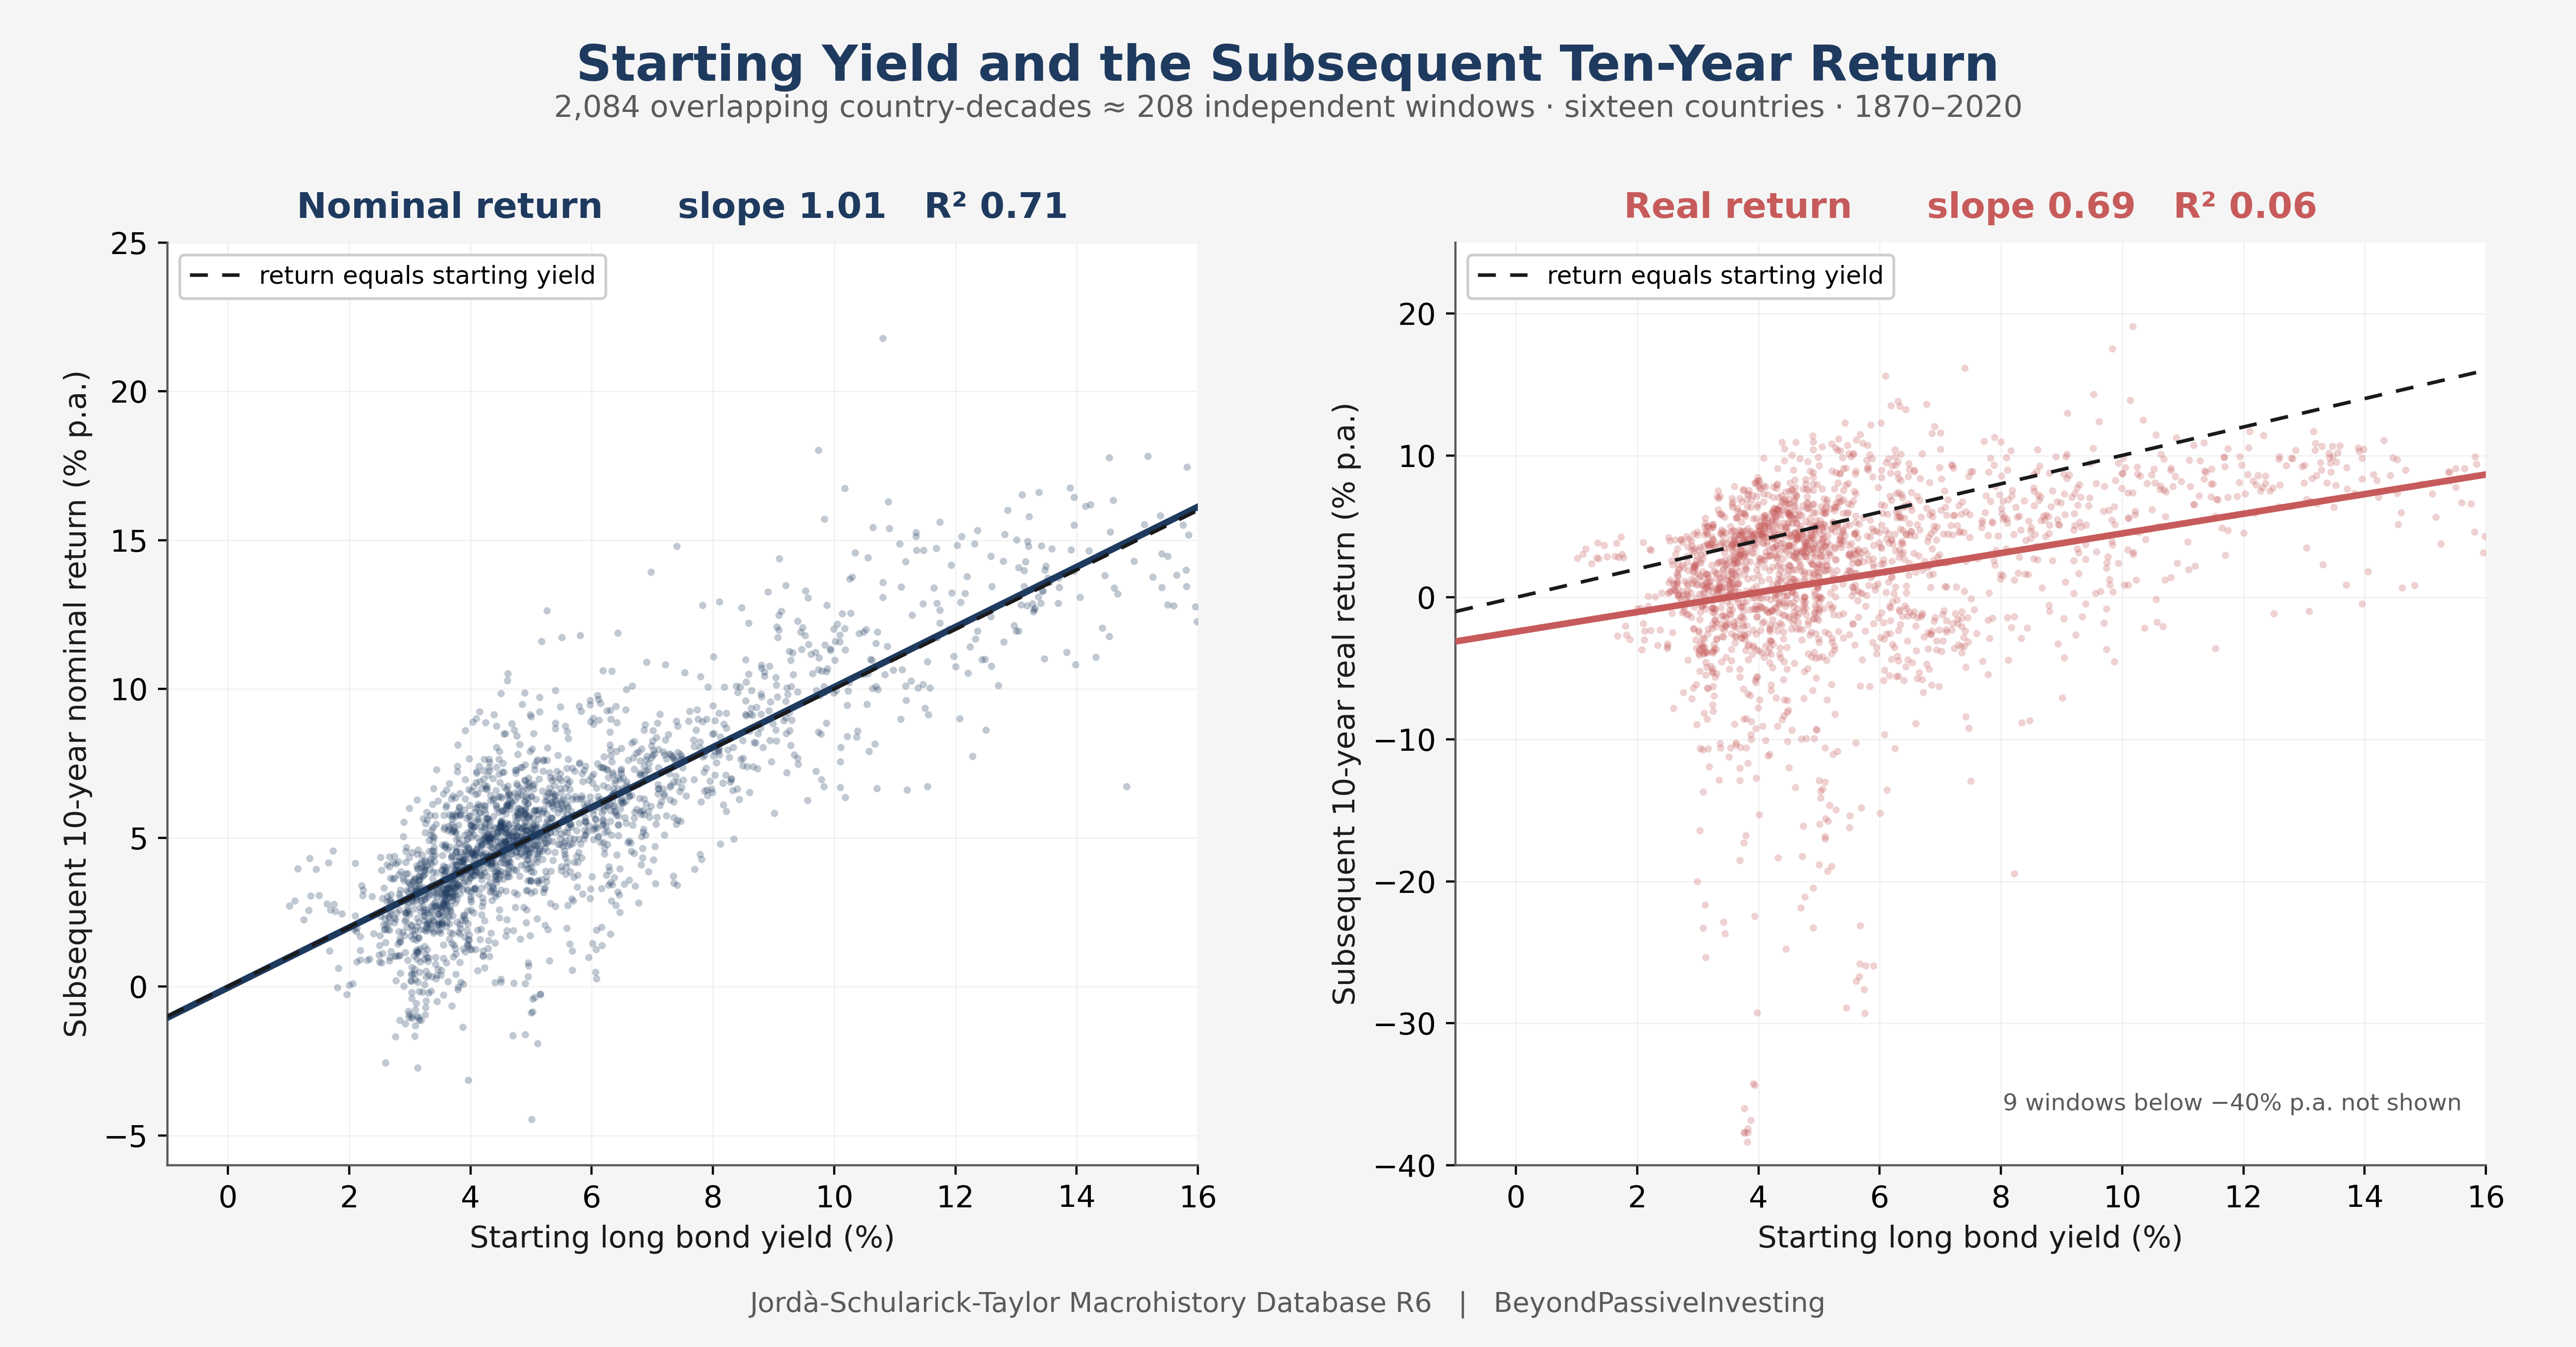
In nominal terms the answer is almost complete. The fitted slope is one and the intercept is zero, which is another way of saying that the yield does not predict the return so much as constitute it. Half of all decades landed within a percentage point of the number available on the day of purchase. The relationship holds under the classical gold standard, through both wars, under Bretton Woods, through the Great Inflation and through the disinflation that followed, with explanatory power that never falls below forty percent in any of those regimes.
The mechanism is arithmetic rather than an anomaly. A portfolio rolled at a duration near the holding period earns its starting yield, because the capital gains and losses accumulated along the way offset one another by the time the horizon closes. There is nothing here for an arbitrageur to remove, which is why the relationship survived a century and a half of institutional change.
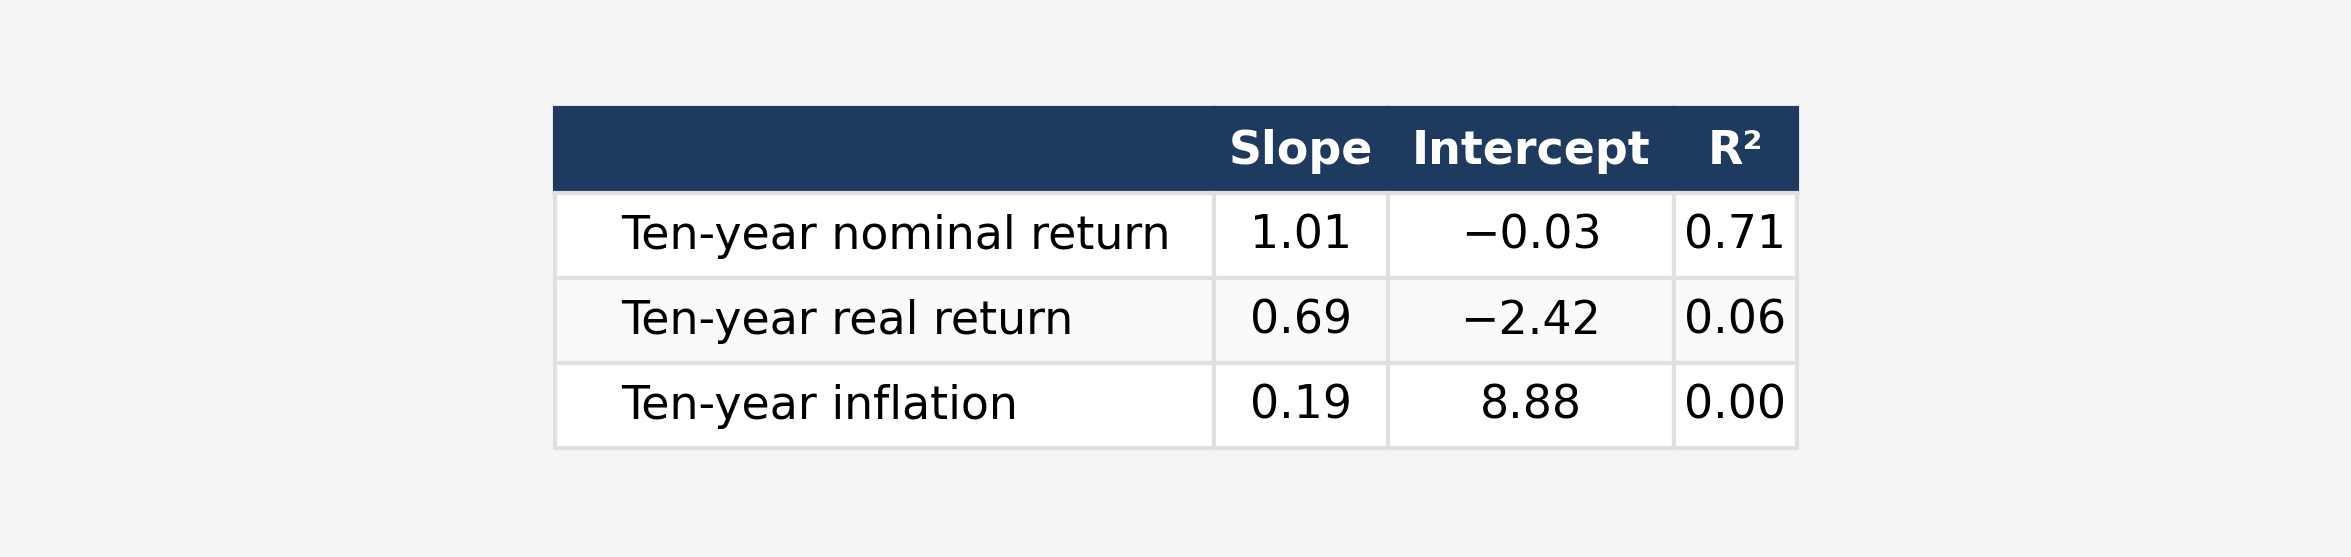
Repeating the exercise on real returns removes almost all of it. Decomposing the variance shows where it went. Inflation accounts for nearly all of the variation in ten-year real bond returns, and bond market behaviour for very little.
The yield offers no compensation for this. Irving Fisher argued that nominal interest rates should embed expected inflation, so that a bond bought at a high yield during an inflationary period would still deliver its real return.[2] Across this panel that adjustment does not appear at a ten-year horizon. Starting yields carry no information about the inflation that followed.
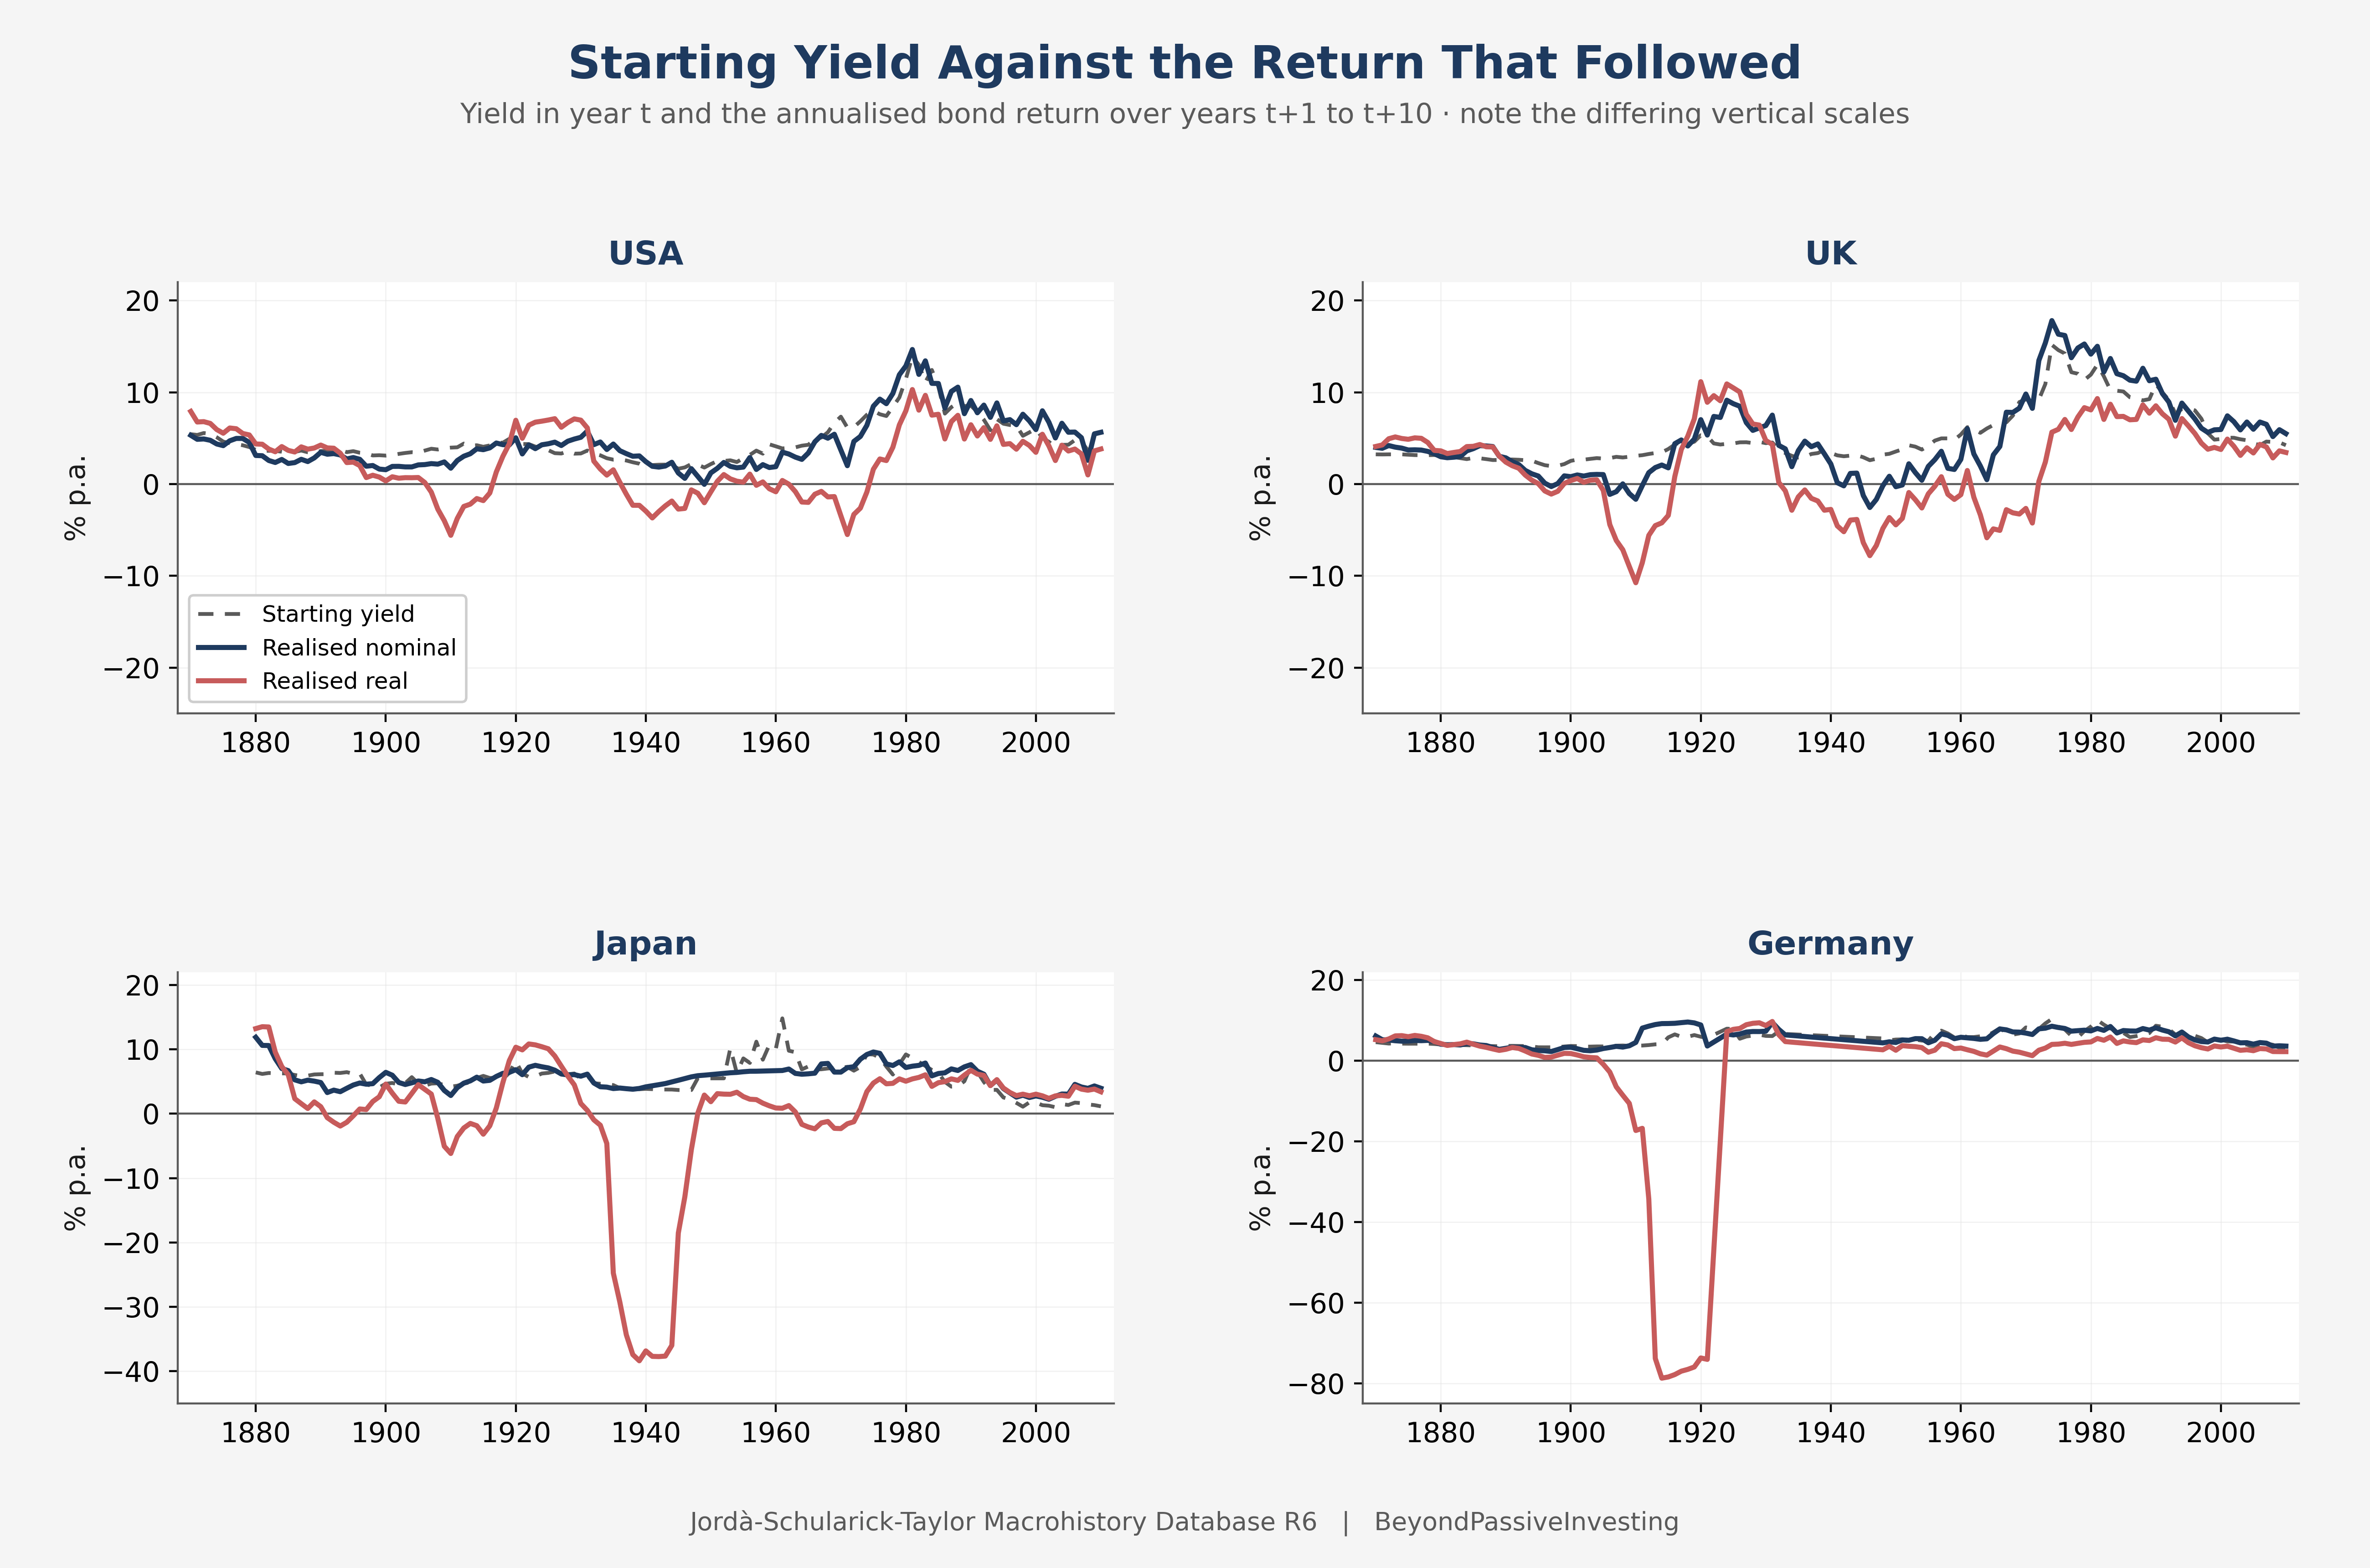
Four countries show the separation. The nominal line follows the yield in every panel. The real line follows it only where inflation stayed low, and departs by five points in the United States, eleven in the United Kingdom, thirty-eight in Japan and seventy-nine in Germany.
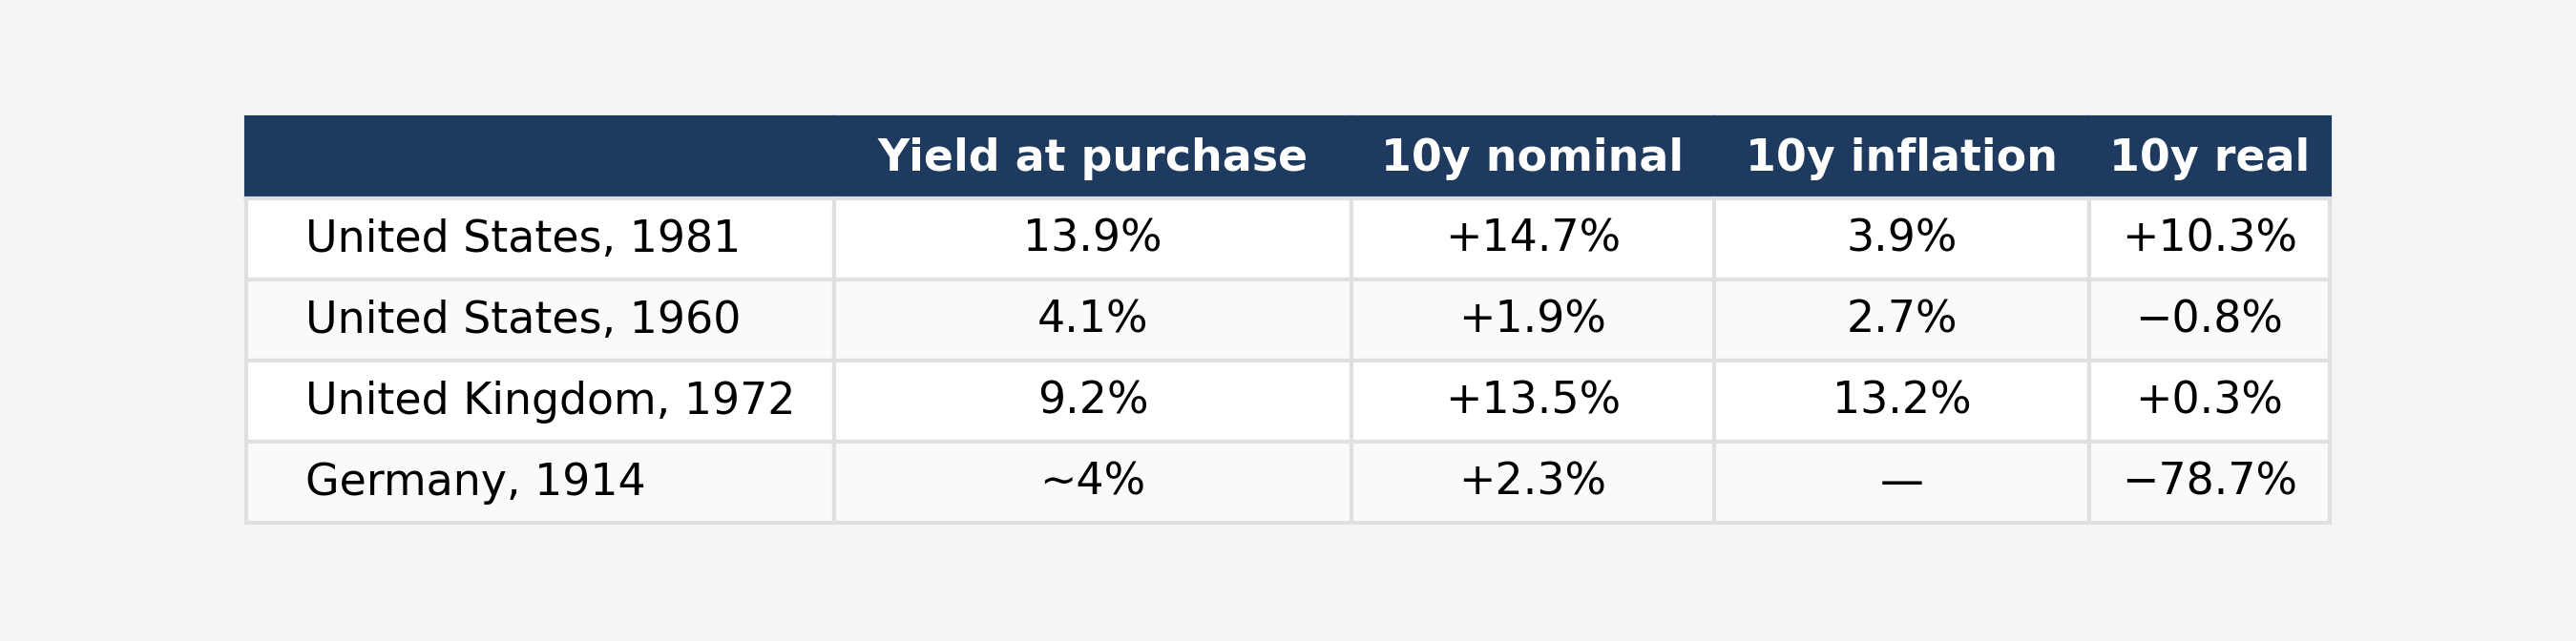
The two American rows are the useful pair, because they carry the lesson without a war attached. A holder in 1981 and a holder in 1960 both received close to what the yield promised. Only one of them kept it.
Two features of the estimate deserve stating. The ten-year windows overlap, so the two thousand observations correspond to roughly two hundred independent decades. And the long-rate series drifts in maturity across the sample, which makes the match to a ten-year horizon approximate.
Carry and repricing
The annual return on a bond portfolio has two parts. The first is the yield carried into the year, which is known in advance and cannot be negative in nominal terms. The second is the price change caused by the yield moving during the year, which is not known in advance and scales with duration. A portfolio with a duration of five years loses roughly five percent of its value for every percentage point the yield rises, and gains the same when the yield falls. I reconstructed this mechanism in detail in the TLT article; here only the consequence matters.
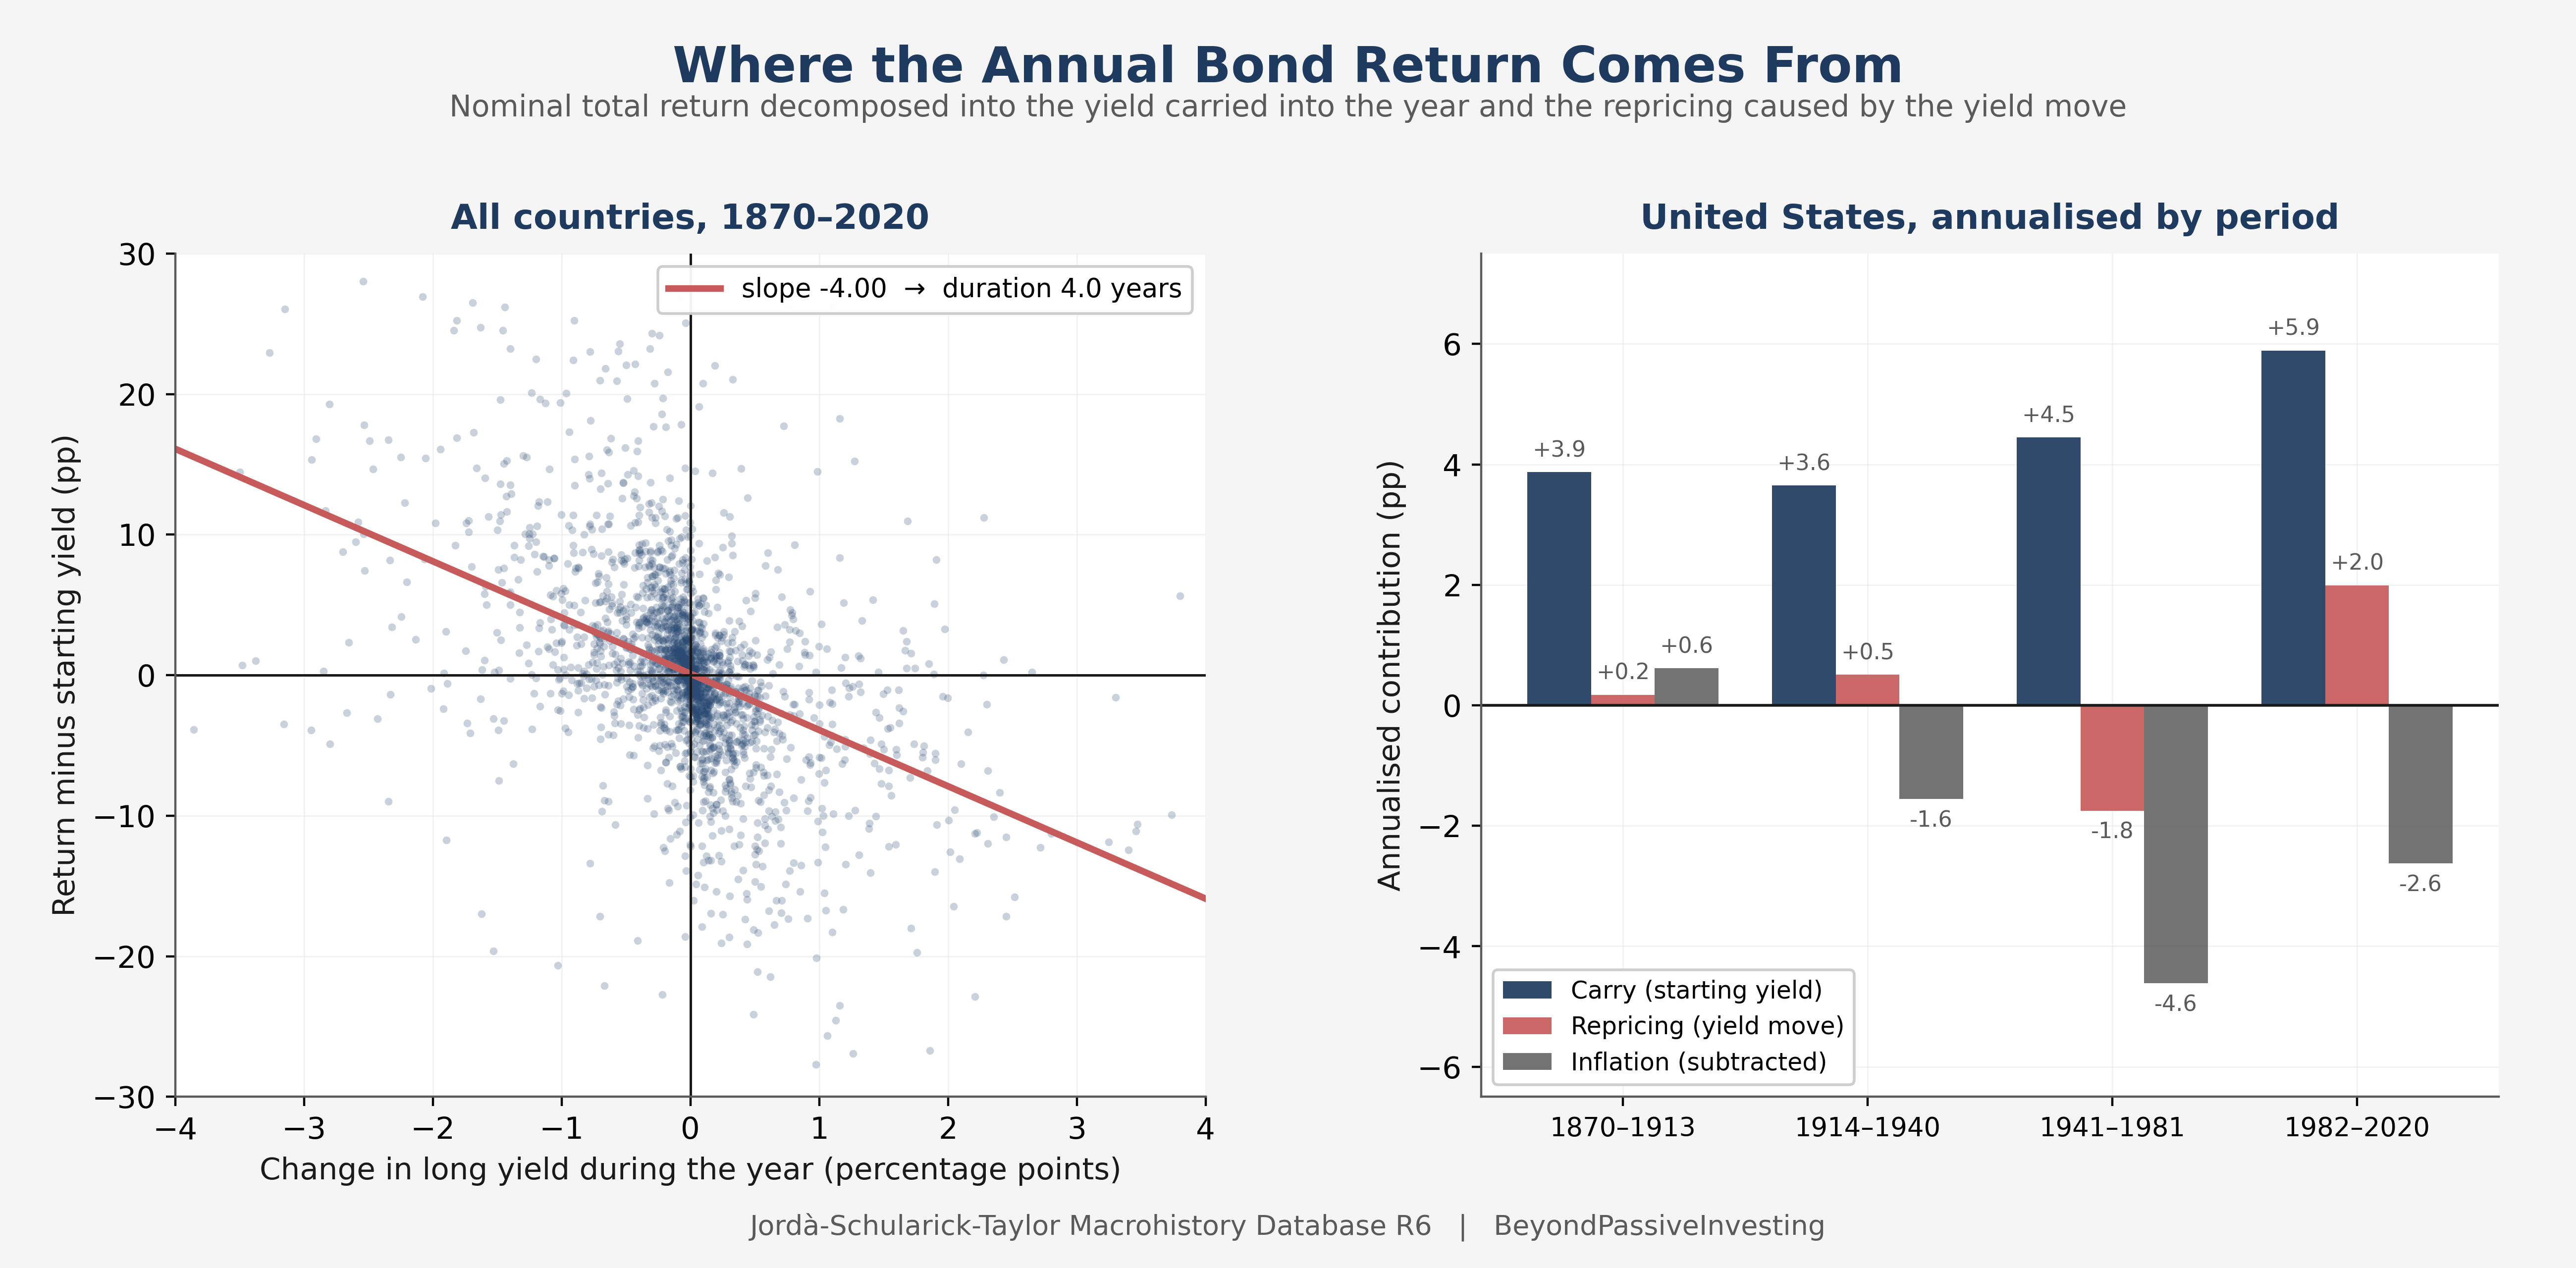
Regressing annual nominal returns on the starting yield and the yield change recovers both parts from the data without assuming either. The coefficient on the yield change is the implied duration: four years across the panel, six for the United States, consistent with the maturities the series tracks.
Sorting country-years by the direction of the yield move separates two different assets. In years when yields fell, bonds compounded at 6.4 percent in real terms. In years when yields rose they lost 1.7 percent. The right panel of the chart shows the same decomposition for the United States across four periods, and the pattern is that carry stayed positive and fairly stable throughout, while repricing and inflation together decided the outcome.
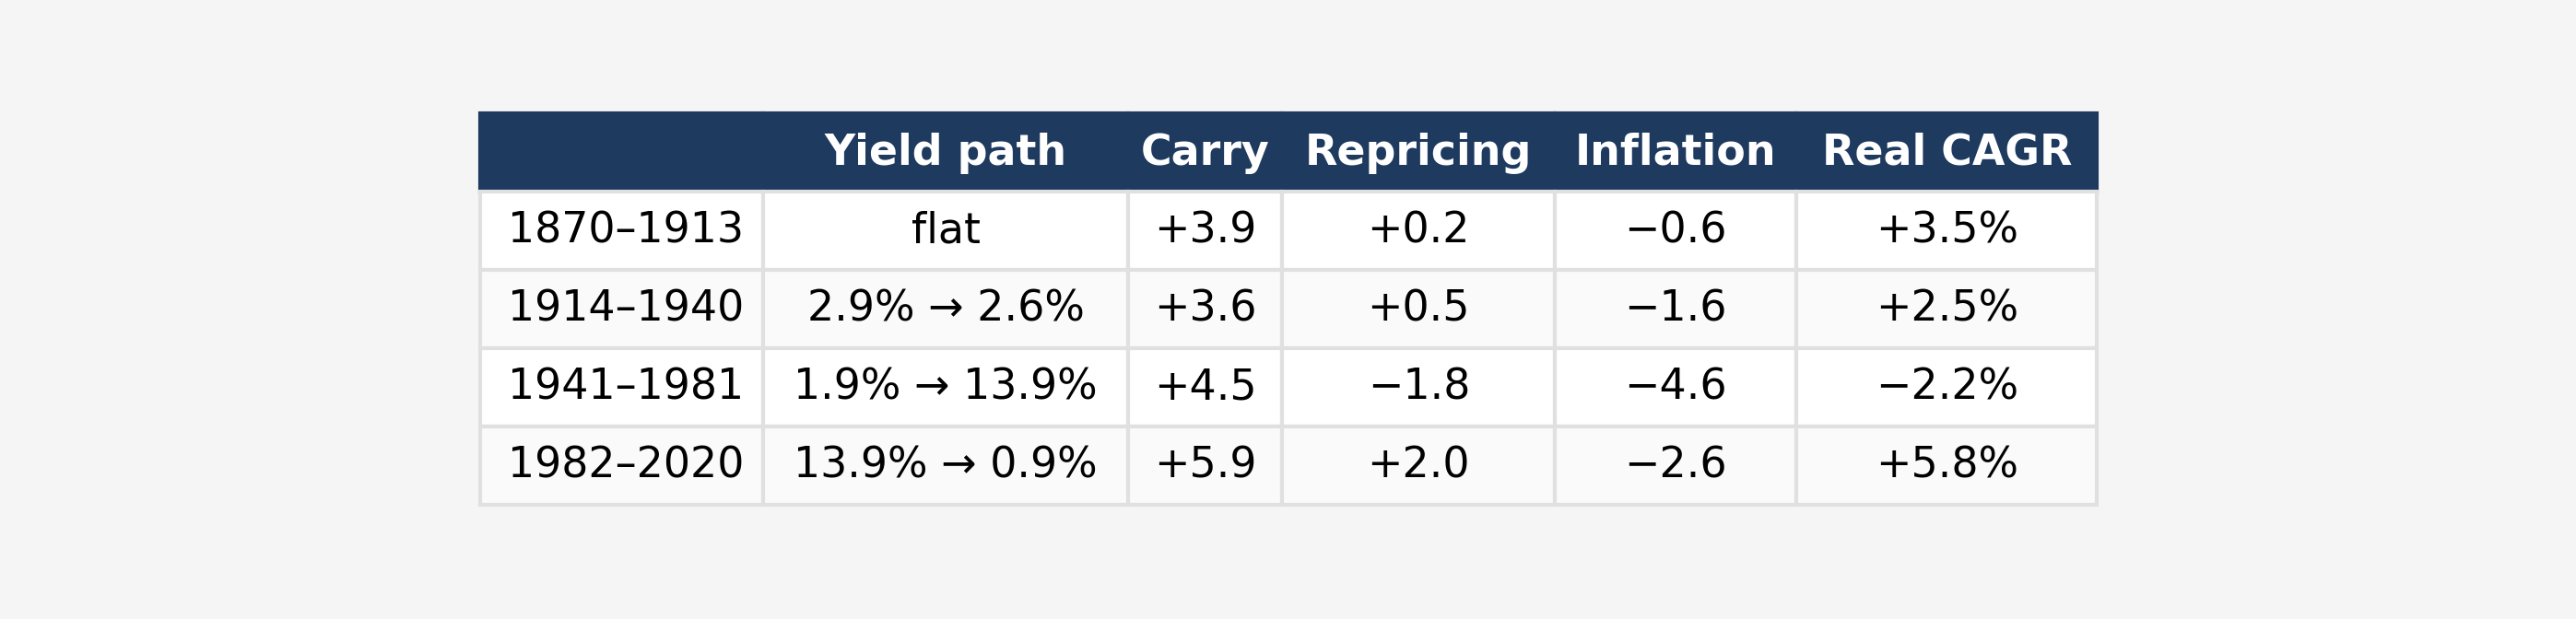
The forty years to 1981 and the forty years after it are the same asset run in opposite directions. That matters for how the evidence is read, because forty years is the whole of a professional career and most of an investor’s accumulation phase. Anyone who formed their understanding of bonds by holding them from the early 1980s onward learned the behaviour of a falling yield, and had no occasion to learn anything else.
Gold, and the difference between a price and a quotation
Gold is the obvious candidate for the asset that escapes this, and testing it requires more care than testing bonds. The series used here is the annual London price compiled by MeasuringWorth, which extends back to 1257 and is quoted in sterling until 1949.[3] For most of the sample that quotation was not a market price. Gold was fixed at 20.67 dollars an ounce until 1932, revalued to 35 dollars in 1934, and held there until 1968. American citizens could not legally hold monetary gold between 1933 and 1974.
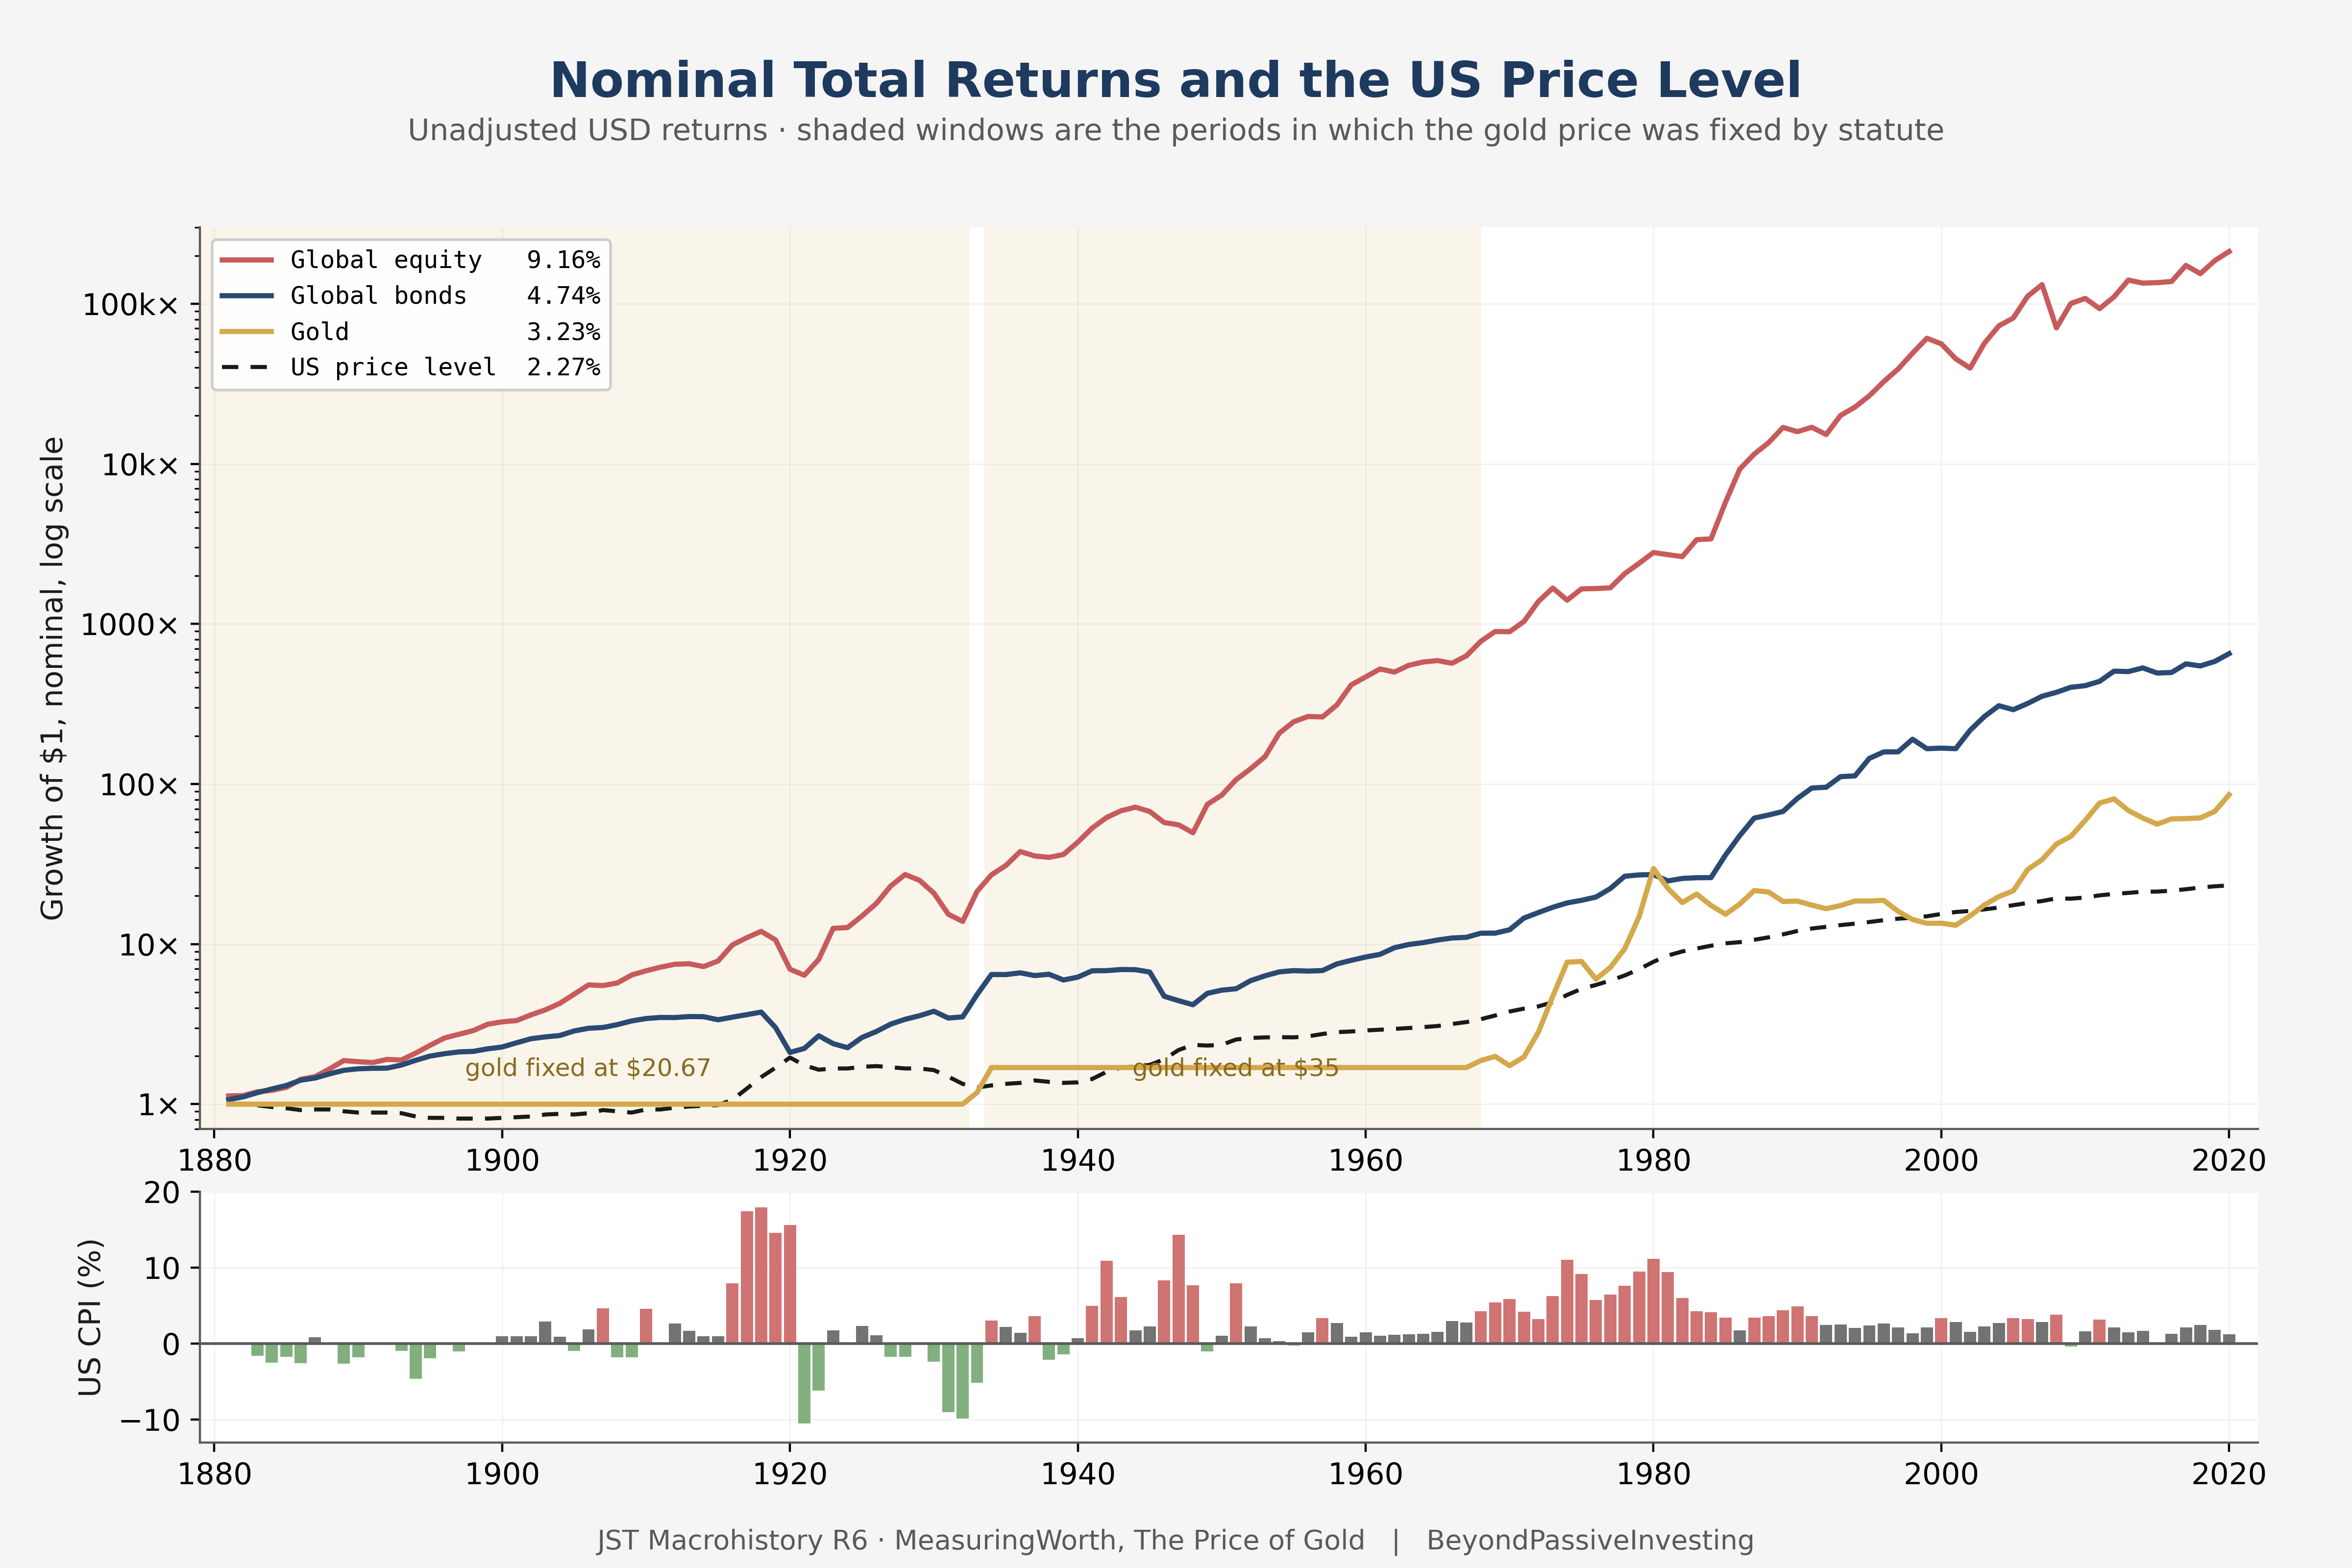
The nominal return is exactly zero in every year inside both peg windows, which is the check that the series has not been back-filled with a quotation that did not exist. Several published gold datasets do exactly that for the years between 1934 and 1967, and the effect is to create a tradeable trend out of an administered number.
Under Bretton Woods gold lost purchasing power at almost precisely the rate of American inflation. This is not a failure of the metal but a definition. A price fixed in nominal terms while the price level rises is a short position in the price level, and it could not hedge inflation because it was not permitted to move. Gold then compounded at more than twelve percent a year for the fourteen years after the peg broke, which is the same adjustment arriving at once.
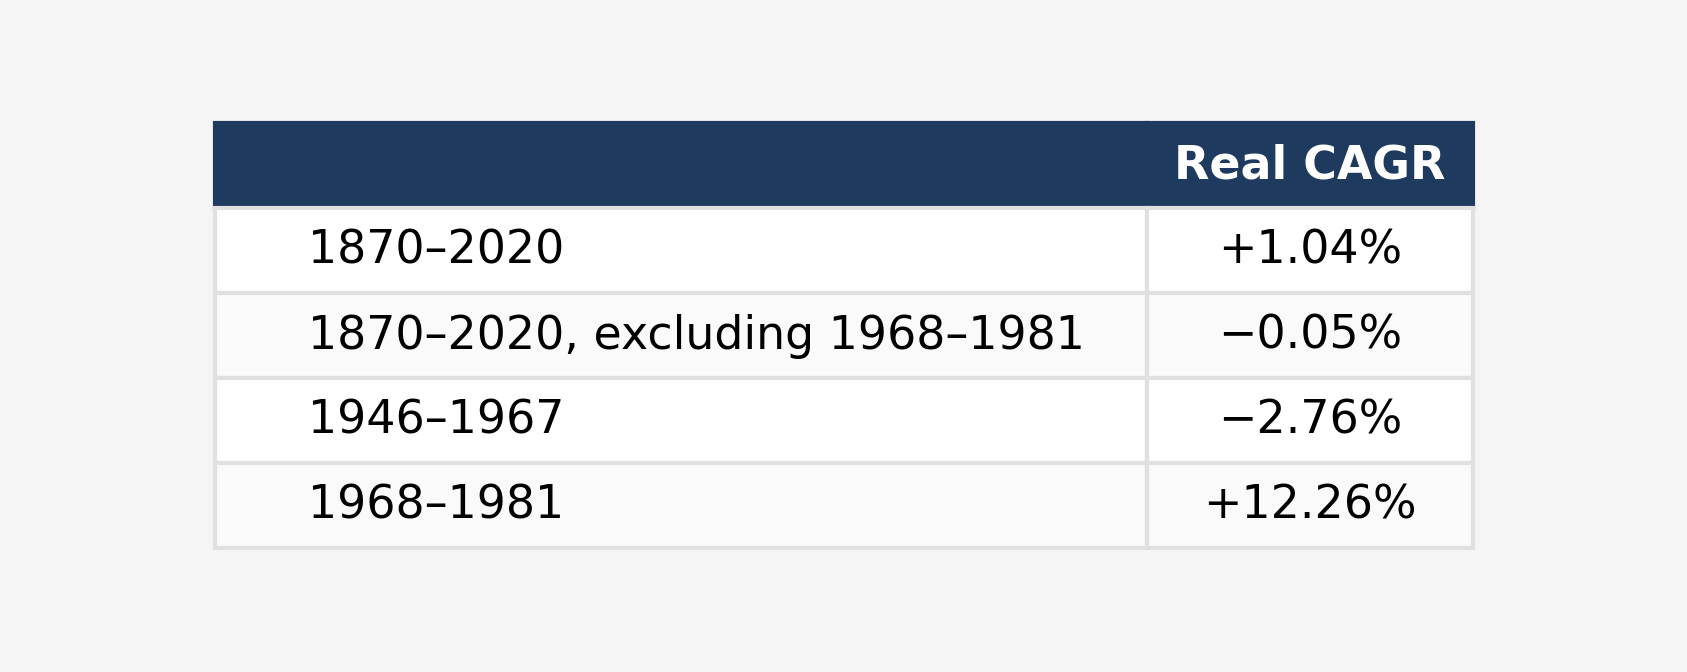
Over the full period gold compounded at 1.04 percent in real terms with volatility close to that of equities. Remove the single window from 1968 to 1981 and the rate is slightly negative. What this database contains is one administrative repricing, not a premium earned repeatedly. Erb and Harvey reach a similar conclusion from the modern floating period, where the real price mean-reverts around a level rather than trending.[4]
The limit of the evidence should be stated plainly. There is no clean observation here of gold as a freely floating asset during a sustained financial repression, because the only sustained repression on record occurred while the price was fixed by statute. That is a gap in the data rather than a verdict on the asset.
Where the damage starts
Each section arrives at the same variable, so it is worth asking whether inflation damages bonds in proportion to its level or whether something changes at a particular point. Sorting every country-year by that country’s own inflation answers it without reference to any single national experience.
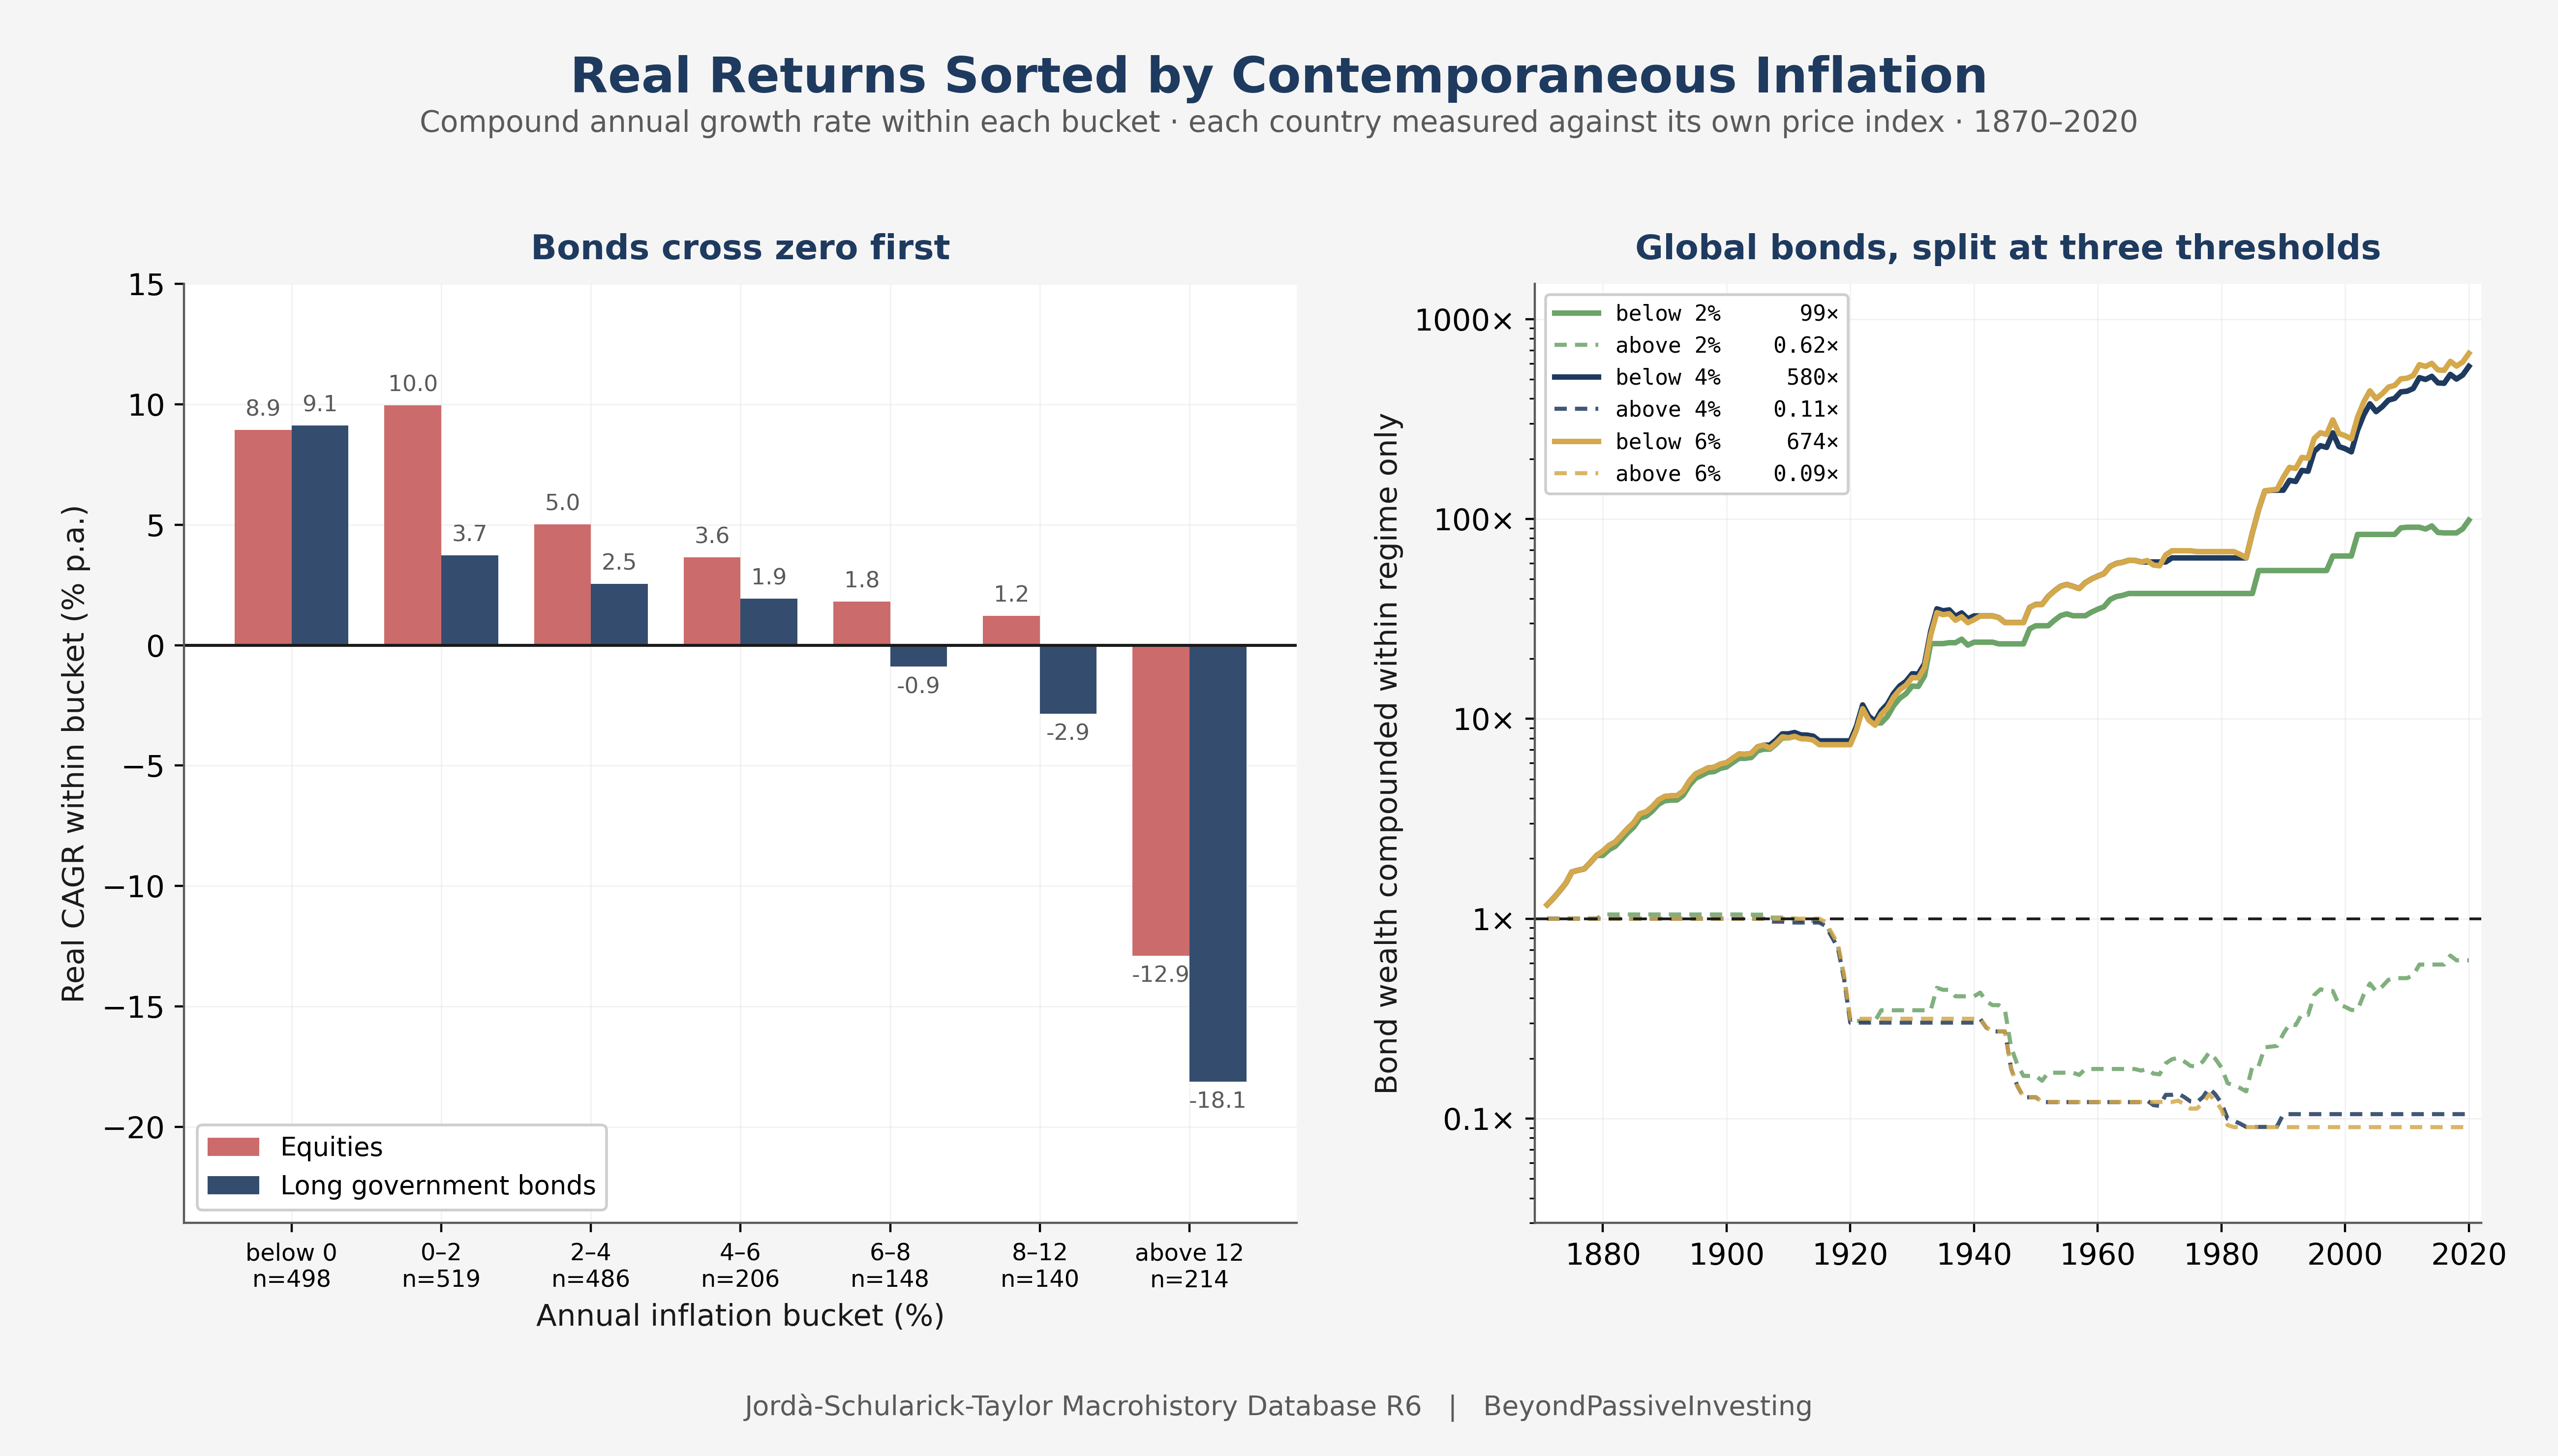
Real bond returns decline steadily as inflation rises and cross zero between six and eight percent. Equities decline more slowly and stay positive until inflation passes twelve. Below two percent the two assets are close to indistinguishable. Above eight they are not the same instrument.
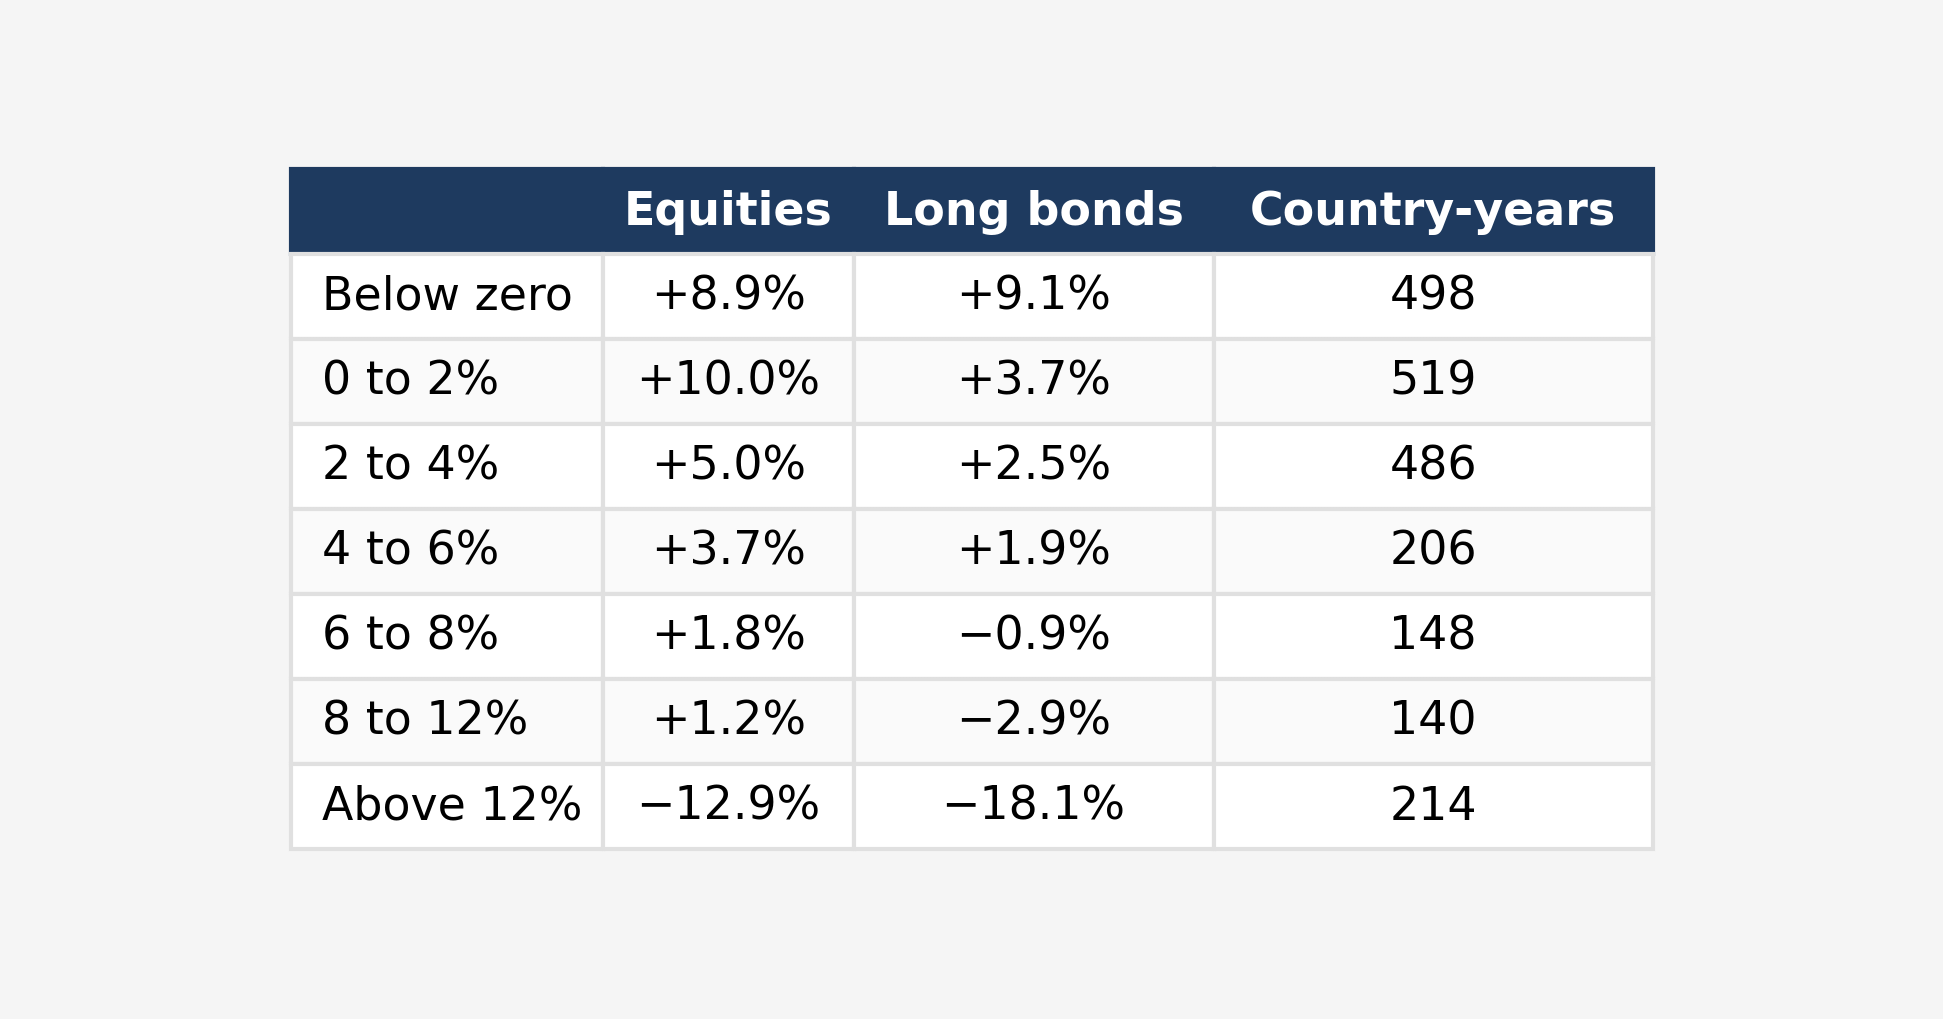
An earlier version of this analysis used a four percent threshold on American inflation, and that figure does not survive contact with the full panel. Four percent describes the United States, which spent little time in the buckets where the damage concentrates. Measured against each country’s own price index the crossing point sits higher, and the decline is gradual rather than sudden.
The right panel separates the two regimes and compounds each on its own, at three candidate thresholds. Whichever line is chosen, the shape is the same. Bond wealth accumulates in the quiet years and is removed in the loud ones, and the product of the two is what the holder received. The threshold changes the arithmetic and not the conclusion.
Equities lose part of their return in high-inflation years and keep the rest, until the highest bucket where both fail together. That difference follows from what the two instruments are. A share is a residual claim on output, priced in whatever currency exists at the time. A bond is a fixed claim in a unit of account that a government controls and, under sufficient fiscal pressure, has an incentive to devalue. Reinhart and Sbrancia document that incentive acting deliberately as policy across the postwar decades.[5]
What is different now
This database ends in 2020, and the six years since have not been a continuation of what preceded them. The inflation of 2021 and 2022 was the largest in four decades, and 2022 delivered a simultaneous real loss in equities, bonds and gold of a kind that appears in this sample roughly one year in seven. That episode sits outside the data used here and should not be read as confirmation of anything in it.
The starting conditions have also moved. The central finding of this article is that the yield at purchase determines the nominal decade, and in 2020 that yield was near one percent across the developed world, with much of Europe below zero. It is not there now. The American ten-year yield sat near 4.7 percent in late August 2026 and the thirty-year above five, with the long end under pressure from issuance rather than from policy expectations.[6] A German investor faces a similar shift at smaller magnitude.
This matters for how the historical result should be applied. The evidence says a bond bought at one percent could not deliver a positive real return under any plausible inflation path, which was an arithmetic statement rather than a forecast. The same arithmetic at 4.7 percent gives a different answer, and one that depends on inflation rather than being settled in advance. The finding concerns the mechanism, not the allocation, and any allocation implied by 2020 conditions expired with them.
What this leaves
Bonds paid the median country 1.62 percent a year after inflation over 150 years. Equities paid 4.52 percent on the same data. So the safe asset earned about a third as much, which is the price of holding a claim with a fixed payment.
What the bondholder is promised in nominal terms is dependable. The yield at purchase turned out to be the nominal return, decade after decade and country after country. What the bondholder keeps after inflation is not dependable at all, because inflation decides how much of that nominal return survives and the yield contains no information about what inflation will do. The buyer knows the first number and cannot know the second.
Inflation also removes the obvious places to hide. It damages bonds first and hardest, but at high enough levels it damages equities too, and gold spent most of this sample legally unable to respond. The three assets fail together rather than in turn.
Holding sixteen countries rather than one did not help either. The governments were suppressing their bond markets at the same time and for the same fiscal reason, so the losses arrived together. That is a correlation in policy rather than in markets, and spreading across borders offers no protection from it.
Which leaves the question for the next article. If the damage concentrates in identifiable conditions, and if those conditions appear in prices before they appear in policy, then the response is not a different asset. It is a rule for holding less of the ones already owned.
Data and construction
Bond, equity and price data are from the Jordà-Schularick-Taylor Macrohistory Database, Release 6, covering sixteen advanced economies from 1870 to 2020.[8] Gold prices are the annual London series compiled by Officer and Williamson at MeasuringWorth, quoted in sterling to 1949 and in dollars thereafter.[3] Current yields are from the Federal Reserve H.15 release of 21 August 2026.[6]
All rates quoted in this article are compound annual growth rates. Real returns are computed as (1 + nominal) / (1 + inflation) − 1, deflating after compounding. Each country runs on a complete annual grid from its first observation, and years with a closed exchange carry a zero nominal return before deflating. Annual returns are floored at −99.99 percent so that cumulative products remain finite. Forward ten-year windows are counted only where all ten years are present; they overlap, so the effective number of independent observations is roughly one tenth of the nominal count.
References
Reinhart, C. M. and Rogoff, K. S. This Time Is Different: Eight Centuries of Financial Folly. Princeton University Press, 2009, chapters on domestic default and currency conversion.
Fisher, I. The Theory of Interest. Macmillan, New York, 1930.
Officer, L. H. and Williamson, S. H. “The Price of Gold, 1257–Present.” MeasuringWorth, 2024. Annual London price series, sterling to 1949 and US dollars thereafter.
Erb, C. B. and Harvey, C. R. “The Golden Dilemma.” Financial Analysts Journal 69(4), 2013, pp. 10–42.
Reinhart, C. M. and Sbrancia, M. B. “The Liquidation of Government Debt.” Economic Policy 30(82), 2015, pp. 291–333.
Board of Governors of the Federal Reserve System. H.15 Selected Interest Rates. Daily release, 21 August 2026.
Jordà, Ò., Knoll, K., Kuvshinov, D., Schularick, M. and Taylor, A. M. “The Rate of Return on Everything, 1870–2015.” Quarterly Journal of Economics 134(3), 2019, pp. 1225–1298.
Jordà, Ò., Schularick, M. and Taylor, A. M. “Macrofinancial History and the New Business Cycle Facts.” NBER Macroeconomics Annual 31, 2017, pp. 213–263. Macrohistory Database, Release 6.
Dimson, E., Marsh, P. and Staunton, M. Triumph of the Optimists: 101 Years of Global Investment Returns. Princeton University Press, 2002.
Ilmanen, A. Expected Returns: An Investor’s Guide to Harvesting Market Rewards. Wiley, 2011, chapters 8 and 9 on bond risk premia.
Btw how do you always write such goated substacks
It would be interesting to see how broad commodities performed in this long history and in the inflationary episodes. I suspect they might have been good at hedging against stocks and bonds.